Over 3 million applications since 2020See the footnote substantiating this figure
Payday loans and bad credit loans
Making it happen.
Borrow £50 to £5,000 with one short form, and repay over 3 to 36 months. A quote won’t affect your credit score.
-
3 million
applications since 2020See the footnote substantiating this figure
-
4,500+
applications a daySee the footnote substantiating this figure
-
Excellent
4.8 out of 5 · 8,130 reviews on
What happens after I click?
- One short form. About 3 minutes, with UK-based bank-grade security.
- A soft search. Your score isn't affected, and no one will call you.
- One offer on screen. Accept it or walk away. We do not charge you a fee for using PaydayUK.
-
4,500+
applications every daySee the footnote substantiating this figure
-
Quick
same-day payout if approved
- CCTA Member
- ico. Registered
- GDPR Compliant
Excellent
4.8 out of 5 · based on 8,130 reviews
- CCTA Member
- ico. Registered
- GDPR Compliant
Representative example: Amount of credit: £500 for 6 months at £100.22 per month (final payment £100.21). Total amount repayable of £601.31 Interest: £101.31 Interest rate: 66.49% pa (fixed). Representative 91% APR. Rates between 9.3% APR and maximum 1292.1% APR - your no-obligation quote and APR will be based on your personal circumstances. Credit broker, not a lender. Payday UK (Payday Loans Ltd) is an appointed representative of Flux Funding Limited, which is authorised and regulated by the FCA (FRN 806333).
About our service
Payday UK is a simple way to find a payday loan or bad credit loan that suits your circumstances, and our service is free to use.
-
Free to use
How we’re paidYou never pay us. If you take out a loan, the lender may pay us a commission. It doesn’t change what you repay.
-
Apply 24/7 online
Start your applicationApply at any time from your phone or computer. One short form takes about 3 minutes, and you never have to accept an offer.
-
3-minute soft search
How eligibility worksChecking your eligibility uses a soft search, so it won’t affect your credit score. A lender only runs a full check if you accept an offer.
-
FCA authorised lenders
Check the FCA RegisterEvery lender on our panel is authorised and regulated by the Financial Conduct Authority. Payday UK is an appointed representative of Flux Funding Limited (FRN 806333).
How payday loans work through Payday UK
Here at Payday UK, we make finding your payday loan or bad credit loan as straightforward as possible to help smooth out life’s road bumps.
-
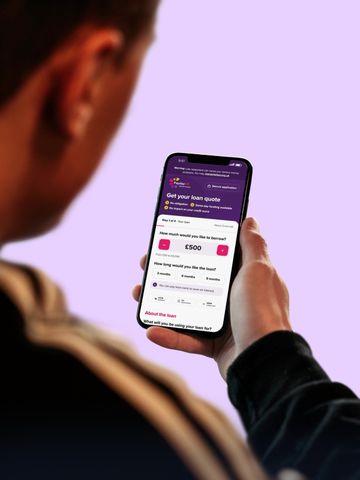
Apply online
Fill out our short, secure form and search a panel of FCA-authorised lenders and brokers to see the offers available to you.
-
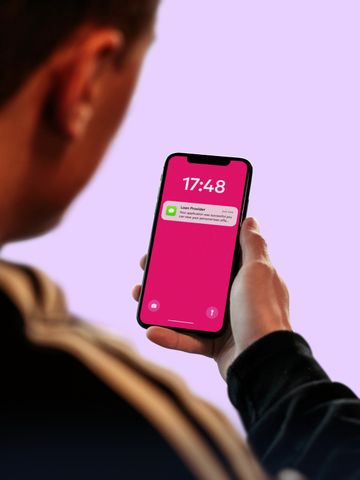
Check your offer
Lenders check what you can afford. Compare the total repayable before you accept.
-
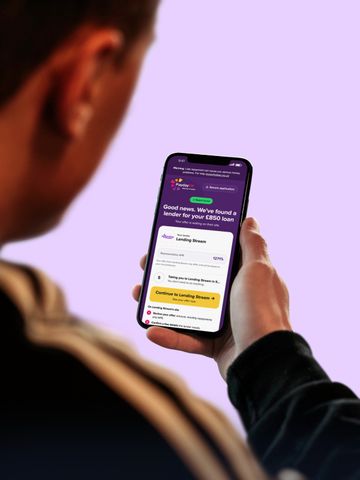
Get your money
If you’re approved and accept, the lender can often pay the same day.
Check your eligibility
Check in 3 minutes. It’s a soft search, so your score isn’t affected.
Check eligibility Soft search. Won’t affect your score
Who we’ve helped and what they think
Rated 4.8 / 5 • 8,130 reviews
Showing our 4 & 5 star reviews
See the full picture: read all our reviews on Trustpilot
Who we are
Here when an unexpected cost comes up
Payday UK helps you find a payday loan when an unexpected cost comes up, whether it's a car repair, a boiler breakdown or an urgent bill.
You fill in one short form, at any time of day, and it reaches our panel of FCA-authorised lenders and brokers. Each lender runs a soft search, which doesn’t affect your credit score. Lenders make the decisions, so approval is never guaranteed.
Our service is free, and you never have to accept an offer. If you take out a loan, the lender may pay us a commission. It doesn’t change what you repay.
What applicants asked for: in October 2026, the most common amount requested through our sites was £401 to £500 (about a quarter of applicants), and the most common term was 3 months (just over a third). These are amounts requested, not lent, and approval isn’t guaranteed. If you’re worried about money, free help is available from MoneyHelper.
Payday UK is a trading name of Payday Loans Ltd (FRN 921539), an appointed representative of Flux Funding Limited, which is authorised and regulated by the Financial Conduct Authority. Payday UK is a credit broker, not a lender. You can check our details on the FCA Register.
Loans for bad credit based on what you can afford
Payday UK searches a panel of FCA-authorised lenders, some of which consider loans for bad credit. They look at what you can afford now, not only your past borrowing.
Who loans for bad credit are for
Bad credit loans are for people whose past borrowing makes some lenders hesitate, such as missed payments, a default, a county court judgment (CCJ) or a thin credit file. Some lenders on our panel consider applications like these. Others don’t, so not every application gets an offer. These loans work like any other: you borrow a fixed amount and repay it monthly over 3 to 36 months.
What affects whether you’re accepted
Payday UK is a credit broker, so the lenders on our panel make the decision and approval isn’t guaranteed. These are the main things they look at.
-
Affordability
Lenders compare your income with your regular outgoings to check the repayments fit your budget, often using Open Banking with your permission.
-
Credit history
Lenders look at how you’ve managed credit before. Some on our panel consider missed payments, defaults or CCJs.
-
A regular income
Income from work, self-employment, a pension or some benefits helps show you can keep up repayments for the whole term.
-
Existing commitments
Current loans, credit cards and other debts are counted alongside the new repayments.
What to expect from a bad credit loan
With a poor credit history, you may be offered a smaller amount or a higher rate than someone with a clean record. Some lenders won’t make an offer at all, and approval isn’t guaranteed. Bad credit loans usually cost more, so compare the total repayable across your offers before you accept.
Pros and cons
Pro: lenders weigh what you can afford now, not only your history.
Pro: fixed monthly repayments over 3 to 36 months.
Con: usually cost more than mainstream credit.
Con: you may be offered less than you asked for.
Con: missed payments add charges and harm your credit file.
Checking your eligibility
When you check your eligibility through Payday UK, lenders run a soft search, which doesn’t affect your credit score. A hard search only happens if you accept an offer and the lender runs its full checks. So you can see where you stand before you commit.
Before you borrow
If you're already behind on bills or other debts, a bad credit loan can make things harder. Free, confidential debt advice is available from independent organisations. For more on your options, it's worth reading up on how to get a loan with bad credit.
Repaying on time
Repaying on time is recorded on your credit file and can help over time. Missing payments does the opposite and can lead to extra charges. Only borrow what you’re sure you can repay every month, for the whole term.
If you’re declined
If a lender declines your application, don’t apply again straight away, because several applications close together can make lenders more cautious. Check your credit file, look at the alternatives to borrowing, and talk to a free debt adviser if you’re borrowing to cover bills.
Check your credit file first
You can see your credit report free from the three UK credit reference agencies: Experian, Equifax and TransUnion. Correct any mistakes before you apply.
Popular amounts and terms
These are the most popular amounts through Payday UK. Many customers borrow £300 over 3 months or £500 over 6 months for a one-off cost. Others choose £1,000 over 12 months, or £2,000 over 24 months to spread a bigger bill. Only borrow what you can comfortably repay.
Representative 91% APR.
Payday loans explained
Before you apply for a payday loan through Payday UK, check the answers to these common questions.
What is a payday loan?
The name comes from loans that were repaid in one go on your next payday. Those have almost disappeared in the UK. Today, a payday loan is a short-term loan for a cost you didn’t plan for, like a car repair or a broken boiler. Through Payday UK you borrow £50 to £5,000 and repay in monthly instalments over 3 to 36 months.
You can repay early at any time, in full or in part, and you’ll pay less interest if you do. So if you can clear it on your next payday, you can. Only borrow if you can afford every repayment over the full term, in case things change. The FCA price cap applies to high-cost short-term credit: loans with an APR of 100% or more, repaid within 12 months.
How much can you borrow, and for how long?
You can apply for £50 to £5,000, over 3 to 36 months. Many people borrow a small amount for a few months, such as a £100 loan or a £300 loan. For a bigger cost, a £500 loan or a £1,000 loan can be spread over longer. The amount you’re offered depends on what you can afford.
What a payday loan costs
Payday loans cost more than most other borrowing, so check the numbers first. The representative example shows a typical loan and the total repayable. If your loan counts as high-cost short-term credit, the FCA price cap applies. Interest and fees can’t be more than 0.8% of the amount borrowed per day. You’ll never repay more than twice what you borrowed.
Who can apply
You can apply if you’re 18 or over, live in the UK, have a regular income and have a UK bank account. Your income can come from work, self-employment, a pension or some benefits. Lenders look at what you can afford now, so a patchy history doesn’t rule you out. Each lender has its own loan eligibility criteria, and some consider payday loans for bad credit.
How applying works
You fill in one short form, which takes about 3 minutes, at any time of day, instead of going to payday lenders in the UK one by one. Lenders run a soft search to give you a quote, which won’t affect your credit score. Approval isn’t guaranteed, because every lender checks you can afford the repayments. If you’re approved and accept an offer, the money can arrive the same day.
How payday loan repayments work
Your repayments are taken from your bank account on the same date each month. If you can, pick a date just after you’re paid. You can repay early at any time and pay less interest. If you’re worried about making a payment, talk to your lender as soon as you can.
How Payday UK compares
One short form, a soft search and offers from a panel of lenders. Here’s how that compares with the other ways to borrow.
-
Our service
Payday UK
Credit broker, free to use
-
 How much could you borrow?
- £50 to £5,000
- How you repay
- Monthly, over 3 to 36 months
- Checking your eligibility
- Soft search, so your credit score isn’t affected
- Lenders who see your application
- A panel of FCA-authorised lenders and brokers, from one form
- Fee for the service
- None. The lender may pay us a commission
- Cost
- Representative 91% APR. Some loans are covered by the FCA price cap
- Who can apply
- 18 or over, UK resident, regular income. Some lenders consider bad credit
Get your quoteWon’t affect your credit score · Representative 91% APR
Approval isn’t guaranteed -
-
Traditional payday loan
One lender, repaid in one go
- How you repay
- In one go, on your next payday
- Checking your eligibility
- Depends on the lender
- Cost
- FCA price cap: 0.8% a day, and the total cost can’t be more than the amount borrowed
- Who can apply
- Depends on the lender
-
Credit union loan
Member-owned, not-for-profit
- How you repay
- Weekly or monthly
- Checking your eligibility
- Depends on the credit union
- Cost
- Interest capped at 42.6% APR in Great Britain
- Who can apply
- Members only, usually by where you live or work
If you can borrow from a credit union, it’s often cheaper. See alternatives to a payday loan
Find the right type of loan
Payday UK can help you find several types of loan. You can borrow from £50 to £5,000, over terms typically from 3 to 36 months.
Short term loans: borrowing spread over a few months.
Same day loans: when the money needs to arrive today.
Quick loans: how a fast lending decision works.
Instalment loans: compare terms and monthly costs.
No credit check loans: why every lender checks your credit.
Alternatives to a payday loan
A loan isn’t always the cheapest option. Check these first. Our Money Hub guide to alternatives covers each one in more detail.
Credit unions: not-for-profit lenders owned by their members, with interest capped by law.
Budgeting Advance: an interest-free advance for some Universal Credit claimants, repaid from future payments.
Employer salary advance: some employers will pay part of your wages early.
Arranged overdraft: ask your bank first; it can cost less for a short gap.
Important information and responsible borrowing
Before you take out a payday loan, check its APR and the total repayable, understand the FCA price cap, and only borrow what you can repay.
It’s important to understand the terms of any loan. Payday loans typically have high APRs because they’re short-term borrowing. For example, the representative APR is 91%.
The FCA price cap applies to high-cost short-term credit: loans with an APR of 100% or more, repaid within 12 months. In plain words: interest and fees can’t be more than 0.8% of the amount borrowed per day, default fees can’t be more than £15, and you’ll never repay more than twice what you borrowed. A loan repaid over more than 12 months isn’t covered by the cap.
See our guide to APR explained for how APR and the cap work. Always read the lender’s agreement before you sign.
Free, independent debt help
If you are struggling with debt, or thinking of borrowing to repay other debts, get free advice first. It is confidential and will not affect your credit file.
-
MoneyHelper
Free, impartial money and debt guidance, backed by government, including a debt advice locator.
-
StepChange
Free, confidential debt advice and managed debt plans, online or over the phone.
-
National Debtline
Free, independent advice on dealing with debts, with fact sheets and sample letters.
-
Citizens Advice
Free help with debt, benefits and housing, in person, by phone or online.
0800 144 8848 (England; Wales 0800 702 2020)
Our helpful guides
These guides will help you manage your money and learn more about the types of loans available.
-
Can a young person get a loan with no credit history? What lenders check, how to build credit from nothing, and the cheaper options to try first.
-
Learn what your borrowing options are when you're between jobs.
-
Explore government support, interest-free advances and responsible borrowing options if you're receiving benefits.


Questions about payday loans and loans for bad credit
Is Payday UK a lender or a broker?
Payday UK is a credit broker, not a lender. We pass your application to a panel of FCA-authorised lenders and brokers and show you any offers. Using us is free. If you take out a loan, the lender may pay us a commission, which doesn’t change what you repay.
Is Payday UK legit and still trading?
Yes. Payday UK is a trading name of Payday Loans Ltd (FRN 921539), an appointed representative of Flux Funding Limited, which is authorised and regulated by the Financial Conduct Authority (FRN 806333). Since 2020 we’ve processed more than 3 million applications, and we’re rated 4.8 out of 5 from 8,130 reviews on Trustpilot. You can check our details on the FCA Register.
Can I get a payday loan from a UK direct lender?
Yes, through Payday UK. We’re a credit broker, and our panel of FCA-authorised lenders and brokers includes direct lenders. One short form reaches them all, and any loan you accept is with the lender, not with us. Using us is free. Our guide explains the difference between direct lenders and brokers.
Are payday loans still legal in the UK?
Yes. Payday loans are legal in the UK and regulated by the Financial Conduct Authority. Every lender must be FCA-authorised and must check you can afford to repay. The FCA price cap applies to high-cost short-term credit: loans with an APR of 100% or more, repaid within 12 months. Under the cap, interest and fees can’t be more than 0.8% a day, and you’ll never repay more than twice what you borrowed.
Who will give me a loan if no one else will?
Some FCA-authorised lenders consider people who’ve been turned down elsewhere, including those with missed payments, defaults or CCJs, if the repayments are affordable now. No lender can promise approval. If you’ve been declined several times, don’t keep applying. Speak to a free debt adviser, such as StepChange or National Debtline, first.
What is the easiest loan to get with bad credit?
No loan is easy to get with bad credit, and no lender can promise approval. Lenders that focus on what you can afford now, not only your history, are more likely to consider you. If you’re a member, a credit union may also help.
Is it possible to borrow money without a credit check?
No. Every FCA-authorised lender must check that you can afford to repay, so a legitimate loan always involves a check. When you check your eligibility, lenders run a soft search, which doesn’t affect your credit score. The lender runs a full check only if you accept an offer.
Can I get a short term loan for 1 month?
Not through Payday UK: short term loans from lenders on our panel run from 3 to 36 months. You can repay early at any time with no early repayment fee, so if you clear a 3-month loan after one month, you’ll pay less interest.
Do I have to repay my payday loan on my next payday?
No. Loans from lenders on our panel are repaid monthly over 3 to 36 months. You have a legal right to repay early, in full or in part, and doing so means you pay less interest. So if you’d rather clear it on your next payday, you can. Ask your lender for a settlement figure to see exactly what you’d pay.
How quickly could I get the money?
If you’re approved and accept an offer, many lenders can pay the same day. Timing depends on the lender’s checks, when you accept and your bank.
What do I need to apply for a payday loan?
You need to be 18 or over, live in the UK, have a regular income and have a UK bank account. Income can come from work, self-employment, a pension or some benefits. Each lender also checks that the repayments are affordable for you.
Can I apply if I’m self-employed or on benefits?
Yes. Self-employed income and some benefits can count as regular income. Lenders may ask for bank statements, or use Open Banking, to check what you can afford.
Can I pay off my loan early?
Yes. There’s no early repayment fee, and repaying early means you pay less interest overall. The law allows a lender to include up to 28 days’ interest in a settlement figure, so ask your lender for the exact amount.
What happens if I can’t make a payment?
If you realise you’ll struggle to make a payment, contact your lender immediately. Many lenders can arrange a payment holiday, adjust your repayment schedule, or work out a temporary solution.
Ignoring missed payments makes the situation worse. Lenders can charge late payment fees, and missed payments damage your credit score.
What are the downsides of a payday loan?
Payday loans usually cost more than mainstream credit, and missing a payment adds charges and harms your credit file. They aren’t right if you’re borrowing for everyday bills or to repay other debts, if the repayments won’t fit your budget every month, or if your income isn’t stable. Get free debt advice first. It’s confidential and won’t affect your credit file.
