Trusted by 3 million UK customers
Small loans from UK lenders
Small loans from £50, borrowed properly and repaid over a term you choose.
What happens after I click?
- You complete one short, secure form.
- A soft search checks your eligibility. Your credit score isn't affected.
- No one will call you.
- If accepted, you see your offer and choose whether to accept.
- We do not charge you a fee for using PaydayUK.
-
4,500+
applications every daySee the footnote substantiating this figure
-
Quick
same day payout available
Excellent
4.8 out of 5 · based on 8,055 reviews
Representative example: Amount of credit: £500 for 6 months at £100.22 per month (final payment £100.21). Total amount repayable of £601.31 Interest: £101.31 Interest rate: 66.49% pa (fixed). Representative 91% APR. Rates between 9.3% APR and maximum 1292.1% APR - your no-obligation quote and APR will be based on your personal circumstances. Credit broker, not a lender. Payday UK (Payday Loans Ltd) is an appointed representative of Flux Funding Limited, which is authorised and regulated by the FCA (FRN 806333).
SMALL LOANS EXPLAINED
What counts as a small loan in the UK?
There's no official limit on a small loan in the UK. The term usually means the amount that closes a gap: a meter top-up, a garage bill, the food shop before payday.
Read more
Payday UK is a credit broker, not a lender. We don't lend money ourselves. One application reaches our panel of FCA-authorised lenders, and you see which may consider you. The smallest amount on our panel is £50.
Small does not mean cheap. Interest on a small amount over a few months is a fixed sum in pounds, but stated as an annual rate it reads as a very large number. The figure to compare is the total in pounds, not the APR.
Small loans are one type of short term loan, borrowed over months rather than years.
Check eligibility Soft search. Won’t affect your score
SMALL LOANS VS AN OVERDRAFT
Is a small loan better than an overdraft?
A small loan is not always better than an overdraft for a short gap. An arranged overdraft used for a few days is often the cheaper option, so check what yours costs before you borrow anything else.
Read more
An unarranged overdraft is not automatically more expensive. Banks now have to charge one annual rate whether an overdraft is arranged or not. Going over your limit can still cost you in other ways. Your bank may charge if a payment is refused, and unarranged borrowing may show on your credit file for other lenders to see. With either type, interest builds daily for as long as the balance stays there.
A small loan has one clear difference: an end date. You agree the amount, the term and the monthly payments before you borrow. Once the final payment is made, the loan is finished. An overdraft has no fixed point where the debt must be cleared.
Neither option is free, and neither is right for everyone. The better choice is the one you can realistically repay, and by a date you can plan around.
If you are weighing them up, MoneyHelper sets out the costs of both and sells you nothing.
Check eligibility Soft search. Won’t affect your score
Apply now
Enter an amount in pounds, from £50 to £5,000.
Will I be approved?
We know you need your money as soon as possible. Check where you stand in 3 minutes with a soft search that leaves no mark other lenders can see.
Check eligibility Soft search. Won’t affect your score
How much should I borrow with a small loan?
Borrow the amount that fixes the problem, not the amount you are offered. A smaller loan costs less and is easier to repay on time, and repaying on time is the whole game.
Read more
Work backwards from the bill. Add up what you are short, not what you would like spare. Then check the payment fits your month before you apply.
Each of the common small amounts has a page of its own:
£50 loans: the smallest amount on our panel, for a meter top-up or a fare to work.
£100 loans: a phone bill, a school trip, a delivery you cannot put off.
£200 loans: a modest repair, or a week of essentials.
£300 loans: a garage bill or an insurance excess.
£400 loans: one bigger repair rather than several small ones.
£500 loans: a larger one-off bill, spread over a term you choose.
Not sure which? Start at the amount you think you need and adjust it in the form. If the timing is the pressure rather than the amount, same day loans and quick loans set out what is realistic.
Which small loan amount do I need for my bill?
Each row is one of our amount pages, with examples of what people borrow that amount for. These are not offers or quotes, and the third column is the question worth answering before you apply.
Read more
| Loan page | The kind of bill it covers | What to check before you apply |
|---|---|---|
| £50 loans | A meter top-up, a fare to work, a school trip | That you can clear it on your next payday |
| £100 loans | A phone bill or a delivery you cannot put off | Whether one payment finishes it instead of four |
| £200 loans | A modest repair, or a week of essentials | Whether a shorter term costs you less overall |
| £300 loans | A garage bill or an insurance excess | That the payment still fits after rent and bills |
| £400 loans | One bigger repair rather than several small ones | That you need the whole amount |
| £500 loans | A larger one-off bill | The total in pounds, not the APR |
Examples only. The amount, term and rate available to you are set by the lender, not by Payday UK.
How do I apply for a small loan online?
You apply for a small loan online with one short form, and Payday UK searches its panel of lenders for you. The part most people want to know about is what happens to their credit file, so that is marked at each step.
One form, one search, no fee to you:
Tell us the amount and the term. It takes about a minute, and you can change the amount before you submit.
We search the panel. Lenders run a soft search to see whether they can help. A soft search won't affect your credit score.
You see who can help. Each offer shows the payments and the total, so you can read them side by side.
You choose, or you walk away. There is no obligation and no fee either way.
You finish with the lender. They run a full credit check at that point. The agreement is between you and them, not us.
We never make the lending decision. Each lender on our panel holds its own FCA authorisation. You can look up any of them, and us, on the FCA Register.
The search itself is quick. Reading the offer properly is the part worth slowing down for.
small loans for BAD CREDIT
Can you get a small loan with bad credit?
Approval is never guaranteed, but a poor credit score does not rule you out on its own. Several lenders on our panel weigh up what you can afford now rather than a score alone.
Read more
Be realistic about the trade. A weak file usually means a higher rate and a lower maximum. Missed payments, defaults and CCJs stay on your file for six years, and some mainstream lenders will decline on the score alone.
What helps an application:
An income the lender can verify, even a modest one.
A settled address and a bank account in your own name.
Asking for less than the maximum.
No recent run of applications elsewhere.
Lenders read your whole credit file, not only the score, so it helps to know how to get a loan with bad credit before you apply.
Check eligibility Soft search. Won’t affect your score
Why does a small loan look so expensive?
The APR on a small loan is high because APR annualises a cost that was never meant to last a year. Borrow a small amount for a few months and the interest is a fixed sum in pounds.
Read more
What to compare instead
The number to compare is the total in pounds. That is the figure that leaves your account. A longer term, such as a 12 month loan, lowers the monthly payment and raises the total, so the two numbers move in opposite directions. The representative example at the top of this page prices one loan end to end. To check the sums yourself, see how APR is calculated.
Rates across the panel run from 9.3% APR to a maximum of 1292.1% APR. Whatever the rate, three numbers on your own agreement tell you what it really costs:
The total repayable: the figure that leaves your account by the end.
The payment dates: whether each one falls after you are paid.
The charge for a missed payment: what it costs you if something goes wrong.
How long should I take to repay a small loan?
The right term for a small loan is usually the shortest one you can afford without needing to borrow again. Short enough to be done with it, long enough that the payment fits.
Read more
Terms on our panel run from 3 months to 36 months. A small amount belongs at the short end. Stretching one over years means paying interest long after the thing you bought has been forgotten.
A shorter term: higher monthly payment, lower total, finished sooner.
A longer term: lower monthly payment, higher total, a longer commitment.
Repaying early: you can repay early at any time and pay less interest.
Common choices are 3 month loans and 6 month loans. Both are instalment loans repaid in fixed monthly amounts.
SPEED, HONESTLY
How quickly can the money arrive?
Nobody can promise you money in a fixed number of minutes. Any broker or lender who does is describing their best case as though it were a rule.
Here is what we can tell you. The search takes about a minute. The decision is usually immediate. Most lenders on our panel aim to send the money the same working day once they have approved you.
Read more
After that it is your bank's turn. Most UK banks support Faster Payments, so it usually appears quickly. Some hold incoming transfers for longer. Weekends and bank holidays slow everything down.
One thing you do control is how ready you are. Have your bank details and your income figures to hand and the form takes a minute. Guessing at them is what sends an application back.
If speed is the whole reason you are here, same day loans and quick loans are more specific about the timings.
Check eligibility Soft search. Won’t affect your score
Can I get a small loan with no credit check?
You can't get a small loan with no credit check from a lender authorised by the FCA, so be wary of anyone who offers one. Every authorised lender has to assess whether you can afford the loan, and it cannot do that without looking at your circumstances.
Read more
What does exist is a soft search, and it is what our panel uses first. A soft search won't affect your credit score and leaves no mark other lenders can see. Only when you accept an offer does that lender run a full check.
So you can find out where you stand before anything touches your score. That is the honest version of what "no credit check" is usually selling.
Three things worth knowing:
An advert promising guaranteed approval is a warning sign, not an offer.
A regulated broker has to tell you about any fee before you pay it, and we never charge you one. Anyone demanding money up front, with no fee agreement in writing, is a warning sign.
You can check any firm on the FCA Register before you share a single detail.
Most adverts for no credit check loans mean a soft search, not no check at all.
What's the difference between a small loan and a payday loan?
The main difference between a small loan and a payday loan is how you repay it. Most small, short-term loans on our panel are what people mean by a payday loan, except that they are repaid in instalments rather than in one lump on payday.
Read more
That difference does matter. One payment out of one wage packet is what used to leave people short the following month. Spreading the same amount over a few months makes each payment smaller and the plan easier to hold.
The name on the advert tells you less than these three things:
How it is repaid: one payment, or several.
The total in pounds: not the monthly figure, and not the APR.
Who you are dealing with: a lender, or a broker searching lenders.
For the wider picture, see how payday loans work, or compare payday loans side by side.
Choosing a small loan
Should I use a lender or a broker for a small loan?
Using a broker such as Payday UK lets several lenders look at one application, while going direct gets you one lender's answer. If it is no, you start again somewhere else, and a direct application often ends in a hard search on your file.
Read more
A broker asks the panel for you, and the searches that produce your offers are soft ones, so they won't affect your credit score. You see several answers together and compare them before any lender runs a full credit check.
We are paid by the lender when a loan completes, not by you. There is no fee to use Payday UK, and no fee if you decide against every offer. That is the thing worth checking with anyone else you use.
There is a trade-off, and it is worth naming. A broker cannot tell you the exact rate before a lender has looked at you, so a panel search gives you breadth rather than certainty.
Our guide to direct lenders and brokers sets out both sides, and no guarantor loans covers borrowing without anyone backing you.
Check eligibility Soft search. Won’t affect your score
Who can apply for a small loan?
Lenders on our panel consider small loan applications from UK residents aged 18 or over with a regular income and a UK bank account.
Every lender on the panel starts from the same basics. You need to:
Read more
be at least 18 years old (see loans for 18 year olds if you're just starting out);
live in the UK;
have a UK bank account and a debit card;
have a regular income the lender can verify;
be able to afford the repayments alongside your other commitments.
Meeting all five does not mean you will be accepted. Every lender runs its own affordability assessment, and it has to. It checks the repayment fits what is left after your bills.
Can I get a small loan if my income is not a wage?
Benefits, self-employment and pensions can all count, but lenders treat them differently and some want to see a few months of it. Panel members look at each kind of income differently, whether you need loans for unemployed people or loans for people on benefits.
Each lender has its own eligibility criteria, and you can check where you stand without committing to anything.
What can I try before I borrow a small amount?
For an amount this small, borrowing is often not the cheapest answer. Some of the options below cost nothing at all.
Read more
Worth ten minutes before you apply:
Ask your employer for an advance: some will bring part of your wages forward, and it costs nothing.
Check your current account: an arranged overdraft for a few days is often cheaper than a loan, and going unarranged adds a refused-payment fee rather than a higher rate.
Speak to whoever you owe: energy suppliers, councils and phone providers have hardship teams who can spread or pause a bill.
Check what you are entitled to: a Household Support Fund grant does not have to be repaid at all, and a DWP Budgeting Loan is interest-free, repaid from your benefits.
Ask about a credit union: many lend small amounts to members, at rates capped by law.
Our guide to emergency money covers these in more detail, and how to borrow money safely is worth reading before any application.
Free, independent debt help
If small loans are becoming a habit, free debt advice is the better next step. It is confidential and will not affect your credit file.
-
MoneyHelper
Free, impartial money and debt guidance, backed by government, including a debt advice locator.
-
StepChange
Free, confidential debt advice and managed debt plans, online or over the phone.
-
National Debtline
Free, independent advice on dealing with debts, with fact sheets and sample letters.
-
Citizens Advice
Free help with debt, benefits and housing, in person, by phone or online.
0800 144 8848 (England; Wales 0800 702 2020)
If you're unsure whether borrowing is right for you, our eligibility criteria page explains who lenders can consider.
WHO YOU ARE DEALING WITH
How Payday UK protects you
We are registered with the Information Commissioner under ZA654345.
Read more
A soft search first, always: checking does not affect your credit score.
No fees to you, ever: we are paid by the lender when a loan completes.
Regulated lenders only: no unauthorised or offshore lenders on our panel.
A real complaints route: with the Financial Ombudsman Service behind it.
If something goes wrong, you have a route. Tell us and we have to acknowledge it, investigate it and answer you within set timescales. If you are still unhappy, the Financial Ombudsman Service will look at it free of charge.
You can contact Payday UK on 0800 302 9409, free from UK landlines and mobiles. Our complaints procedure sets out the steps and the timescales, and responsible lending explains how we approach all of this.
Check eligibility Soft search. Won’t affect your score
Ready to see what you could borrow?
Checking takes about a minute, uses a soft search, and commits you to nothing. You will see what lenders on our panel can offer before you decide anything.
If you decide a loan is not right, that is a reasonable conclusion. Go back to the alternatives above, or speak to MoneyHelper first.
Before you do, run one last check on yourself. Can you make every payment on the dates they fall, without borrowing again to manage it? If the answer is no, a smaller amount or a different option is the better call.
If the answer is yes, go straight to the amount you are after: £50 loans, £200 loans or £300 loans.
How it works
We know you need your money as soon as possible. That's why we have designed our website to be fast and simple.
-
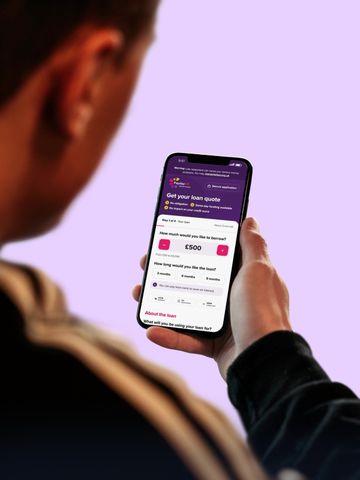
Apply online
Fill out our short, secure form and search a panel of FCA-regulated lenders to see the offers available to you.
-
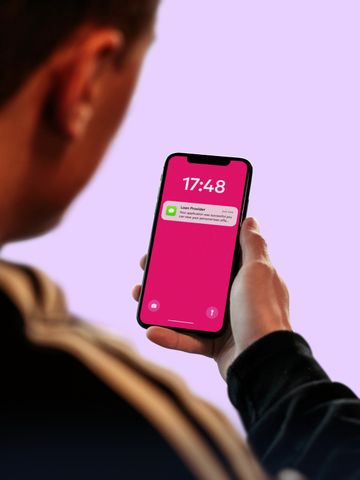
Check your offer
Once you have your offer from the lender, you can review the offer and get your cash.
-
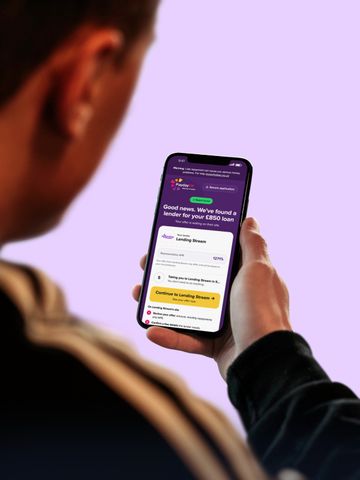
Get your money
Once accepted, your money can often be paid into your account the same day.
We've helped out thousands of people...
Rated 4.8 / 5 • 8,055 reviews
Showing our 4 & 5 star reviews
 Read our reviews on Trustpilot

Small loan amounts and terms
Check eligibility Soft search. Won’t affect your score
Representative 91% APR.
Loan guides
These guides will help you find out more about the different types of loan and lenders available.
-
Need cash fast? Explore quick funding options for financial emergencies.
-
Explore government support, interest-free advances and responsible borrowing options if you're receiving benefits.
-
Learn what your borrowing options are when you're between jobs.


Small loan questions, answered
What is the smallest amount I can borrow?
The minimum you can borrow with a small loan through Payday UK is £50. Fewer lenders offer loans at this level, because arranging one costs them the same as arranging a larger loan. So you'll have fewer offers to choose from at the bottom of the range, and more as the amount goes up.
Are small loans more expensive than larger loans?
Small loans usually have a higher APR than larger loans, but cost less in pounds, because you borrow less for a shorter time. Stating a few months of interest as an annual rate makes the percentage look very large. Compare the total repayable in pounds, not the APR. Seeing how APR is calculated shows why the two figures come apart.
Are small loans only for people with bad credit?
Small loans are not only for people with bad credit. People with good credit use them too, usually because a fixed loan has an end date and a credit card or overdraft does not. The reason for borrowing matters more than the score. Emergency loans for a one-off bill are a reasonable use, a shortfall every month is not.
Is a small loan the same as a payday loan?
A small loan is close to a payday loan, but not identical. Most small loans on the Payday UK panel are instalment loans, repaid over a few months rather than in one payment on your next payday. That keeps each payment smaller. The FCA rules on cost are the same either way.
Can I get a small loan if I am on benefits?
Some lenders on our panel consider small loan applications from people on benefits, and some prefer long-term benefits over temporary ones. Check what government support you can get first, because a grant or a budgeting loan is cheaper than any credit. Each lender looks for something different in benefit income.
Can I get a small loan if I am self-employed?
You can get a small loan if you are self-employed, but you will be asked to evidence your income. Bank statements, accounts or tax calculations usually do it. Lenders look for income that is regular rather than large, so a steady few hundred a month can count for more than an occasional bigger invoice.
Can I repay a small loan early?
You can repay early at any time and pay less interest. No early repayment charge applies to loans arranged through us. Ask the lender for a settlement figure first. It can include up to 28 days' extra interest. Agreements over a year can add a little more.
How many small loans can I have at once?
There is no fixed limit on how many small loans you can have at once. Every lender has to check that a new loan is affordable alongside what you already owe, so running several at once makes the next one harder to get. If you are borrowing to cover borrowing, free help is a better next step than another application.
