Trusted by 3 million UK customers
Unsecured loans
Unsecured loans from £50 to £5000 - no property, no car, nothing of yours put up as security.
What happens after I click?
- You complete one short, secure form.
- A soft search checks your eligibility. Your credit score isn't affected.
- No one will call you.
- If accepted, you see your offer and choose whether to accept.
- We do not charge you a fee for using PaydayUK.
-
4,500+
applications every daySee the footnote substantiating this figure
-
Quick
same day payout available
Excellent
4.8 out of 5 · based on 8,121 reviews
- CCTA Member
- ico. Registered
- GDPR Compliant
Representative example: Amount of credit: £500 for 6 months at £100.22 per month (final payment £100.21). Total amount repayable of £601.31 Interest: £101.31 Interest rate: 66.49% pa (fixed). Representative 91% APR. Rates between 9.3% APR and maximum 1292.1% APR - your no-obligation quote and APR will be based on your personal circumstances. Credit broker, not a lender. Payday UK (Payday Loans Ltd) is an appointed representative of Flux Funding Limited, which is authorised and regulated by the FCA (FRN 806333).
unsecured loans explained
What is an unsecured loan in the UK?
An unsecured loan is money you borrow without putting your home or car up as security. Approval rests on your income and your ability to repay, not on what you own.
Read more
Most everyday credit in the UK is unsecured. Personal loans, credit cards, overdrafts and short-term loans all sit in this category.
No asset is tied to the debt, so nothing you own can be taken automatically if you fall behind. That is the whole difference between unsecured and secured borrowing. The lender has no automatic claim over anything you own. However, they can still pursue the money through collections activity and, in serious cases, through the courts.
Payday UK is a credit broker, not a lender. The lender decides if you qualify, not us. Repayments are worked out in advance at a fixed rate of interest. They are collected monthly and stay the same for the life of the loan.
Check eligibility Soft search. Won’t affect your score
unsecured loans at payday uk
How do unsecured loans work through Payday UK?
Payday UK gives you access to unsecured loans from £50 to £5,000, repaid over 3 to 36 months. We are not the one lending. We introduce you to a panel of direct lenders who write unsecured loans across a range of credit profiles.
Read more
You apply once, and we do the searching. One short application searches our panel of FCA-authorised lenders. You see which of them can work with your circumstances, and you choose from there. Nothing is decided until you accept an offer.
Here's how it works:
You complete the online form, which takes around two minutes
A soft search runs that only you can see on your credit file
We match your details against the criteria of lenders on our panel
You review whatever offers come back, with no obligation to take one
If you accept, that lender runs a full credit check
Once they approve you, funds can arrive the same day
Checking your options with us uses a soft search, so it leaves no mark other lenders can see.
Apply now
Enter an amount in pounds, from £50 to £5,000.
Will I be approved?
We know you need your money as soon as possible. Check where you stand in 3 minutes with a soft search that leaves no mark other lenders can see.
Check eligibility Soft search. Won’t affect your score
How do I apply for an unsecured loan?
You apply for an unsecured loan by filling in one online form, choosing an offer and finishing your application with that lender. It takes a few minutes.
Step 1: Click the apply button and enter basic details including how much you want to borrow and your preferred repayment term. Choose an amount between £50 and £5,000, and a term between 3 months and 36 months.
Step 2: Provide information about your income, employment and monthly expenses. Lenders use it to check any loan would be affordable for you.
Step 3: Submit your application. We search our lender panel, and the lenders run a soft credit check. Within minutes, you will see which lenders have matched with your profile.
Step 4: Review your options. If you find a suitable offer, you can go to the lender’s site to complete your application. If nothing suits you, walk away. Your credit score is not affected.
Step 5: If you accept an offer, the lender will perform a full credit check and make their final decision. Once approved, funds are typically transferred the same business day.
Checking your options with us uses a soft search, so it leaves no mark other lenders can see.
Our online form is open every day of the year, including weekends and bank holidays. Some lenders do not release funds outside banking hours, so a weekend application can settle on the Monday.
Applications submitted during the working day are often funded the same day, while later applications may land the next working morning. And remember, a decline from one lender is not a decline from every lender on the panel. Criteria vary a lot between them, which is the main reason applying through a broker is worth doing.
Unsecured vs secured loans: what's the difference?
The difference between secured and unsecured loans comes down to one thing: a secured loan is tied to something you own, and an unsecured loan is not.
With a secured loan you pledge an asset, usually your home or your vehicle. If you stop paying, the lender has a legal route to take that asset and sell it.
Read more
An unsecured loan carries no such pledge, so renters and people with no significant assets can still borrow.
Here is how the two compare in practice.
Key differences at a glance
Collateral requirements: Secured loans need an asset as security. Unsecured loans do not. This means renters and people without significant assets can still access unsecured borrowing.
Loan amounts: Secured loans often allow higher borrowing because the lender has less risk. Unsecured loans typically offer smaller amounts. Through PaydayUK, you can borrow £50 to £5,000 unsecured.
Interest rates: Secured loans usually have lower interest rates because the collateral reduces lender risk. Unsecured loans carry higher rates to compensate for the increased risk to the lender.
Approval speed: Unsecured loans are typically faster to arrange. There is no need for property valuations or asset verification. You could have funds the same day with an unsecured loan, whereas secured lending often takes weeks.
Risk to you: With a secured loan, you could lose your home or car if you cannot repay. With an unsecured loan, the lender cannot automatically seize your property, but non-payment still has serious consequences. These include damage to your credit score, court action, and potential charging orders that could eventually put your home at risk.
When unsecured loans make more sense
Unsecured loans are often the better choice when:
You need a small loan, typically under £5,000
You need funds quickly and cannot wait for property valuations
You do not own a home or do not want to risk your property
You prefer shorter repayment terms of 3 to 36 months
You want a straightforward application process with minimal paperwork
Secured loans might suit you better if you need to borrow a larger sum, want the lowest possible interest rate, and are comfortable using your home as security. However, the stakes are significantly higher if something goes wrong. Need a larger amount? See £5,000 loans.
Soft credit check only. No impact on your credit score. See your options in minutes.
Can I apply for an unsecured loan with bad credit?
You can apply for an unsecured loan with bad credit. Lenders on our panel look at whether you can afford it now, not just your score. Approval is never guaranteed, and a low score alone does not end an application.
Read more
Our panel includes specialist lenders who focus on current affordability rather than past credit mistakes.
Many people assume that bad credit automatically means rejection. This is not always the case. Lenders in our panel consider factors like:
Your current income and employment status
Your monthly expenses and disposable income
How comfortably you can afford the repayments
Your recent payment behaviour, not just historical issues
Payday UK works with several lenders, so one application reaches them all at once. Each lender applies its own criteria and makes its own decision.
Lenders on our panel start with a soft search. It shows if any may consider you, and other lenders can't see it. A full credit check only takes place when you accept an offer. The steps for how to get a loan with bad credit apply to unsecured loans too.
Rates are higher at the weaker end of the credit spectrum. That is the trade-off for lending without security to a customer the lender sees as a bigger risk.
Factor that into the total cost before you commit. A longer term on a high rate can more than double what you hand back, even on a small amount.
Who is eligible for an unsecured loan?
To apply for an unsecured loan through Payday UK, you will need to meet some basic requirements. These are fairly standard across most UK lenders:
Read more
Be 18 or over
Be a UK resident with a current address
Hold a UK bank account and debit card
Have a regular income from work or self-employment. Some lenders also consider a loan on benefits
Have a valid email address and UK mobile number
Affordability checks are not optional for lenders. FCA rules require them to satisfy themselves that you can meet the repayments before they lend anything.
You do not need to own a home to apply, and you do not need a perfect credit score. Our lenders may also be able to offer you loans without a guarantor.
If you are currently bankrupt or in an Individual Voluntary Arrangement (IVA), you may find it harder to get approved. However, every application is assessed individually, so it is still worth checking your eligibility.
How much do unsecured loans cost?
What an unsecured loan costs depends on the amount, the term and the rate the lender offers you. The figure to check is the total repayable on the agreement the lender shows you, not just the monthly payment.
Read more
Our representative APR is 91%. The representative example at the top of this page shows what a full loan costs.
The actual rate you receive depends on the lender, your personal circumstances, the amount you borrow, and how long you take to repay. APR can range from 9.3% to 1,292.1% across our panel.
You pay us nothing. Lenders pay us a commission when a loan completes, and it does not add to what you repay.
How it works
We know you need your money as soon as possible. That's why we have designed our website to be fast and simple.
-
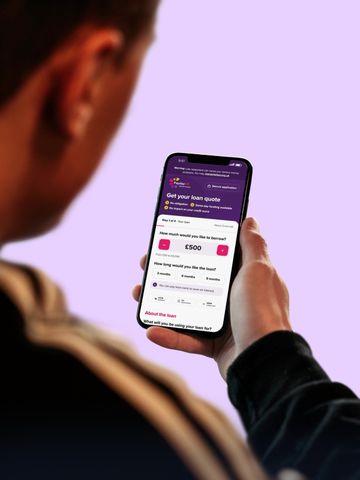
Apply online
Fill out our short, secure form and search a panel of FCA-regulated lenders to see the offers available to you.
-
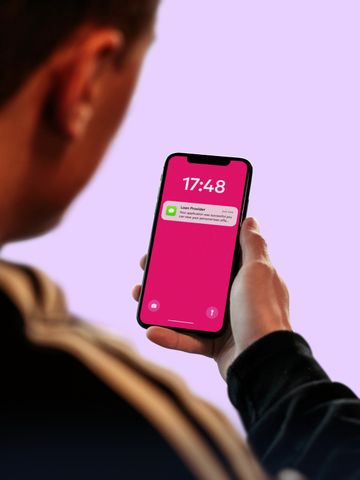
Check your offer
Once you have your offer from the lender, you can review the offer and get your cash.
-
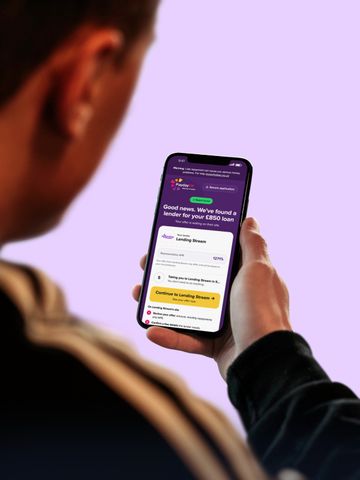
Get your money
Once accepted, your money can often be paid into your account the same day.
Why should I use Payday UK for an unsecured loan?
Using Payday UK means one application searches a panel of FCA-authorised lenders, with a soft search first and no fees to you. Knowing how lenders and brokers differ helps you decide where to apply.
Read more
Here are the advantages of using a broker:
Access to Multiple Lenders: One application reaches our entire panel of FCA-regulated lenders. This saves you time compared to applying to individual lenders one by one, and each lender makes its own decision.
Soft Credit Check Protection: The first check is a soft search. Other lenders cannot see it, and it will not affect your credit score. You only face a full credit check if you choose to go ahead with an offer.
Zero Fees: We never charge application fees, broker fees, or any other charges. If you are ever asked to pay an upfront fee for a loan, treat this as a warning sign of a potential scam.
Same-Day Funding: If your application is approved, most of our partner lenders can transfer funds to your account the same day. Many customers report receiving money within hours of acceptance.
24/7 Availability: Our online application is available every day of the year, including weekends and bank holidays. You can apply whenever it suits you.
What sets our service apart
When searching for unsecured loans in the UK, you will find countless options. What makes Payday UK different is that one form reaches a whole panel of lenders.
Read more
Your details are matched against each lender's criteria in real time, so the results reflect your circumstances.
What happens if I can't repay my unsecured loan?
If you can't repay your unsecured loan, missed payments are reported to the credit reference agencies and the lender can pursue the debt, but most lenders would rather agree a plan with you first.
Read more
Contact your lender immediately. Lenders have to treat you fairly, and many will agree a plan before arrears build. They may offer a payment holiday, reduced payments or an extended term.
Missing payments will affect your credit score and could make it harder to borrow in the future. Late payment information stays on your credit file for up to 6 years.
Under FCA rules, lenders must treat customers fairly and show forbearance if you are experiencing financial difficulty. You have rights, and lenders have responsibilities.
If your debt becomes unmanageable, get free debt advice. An adviser can help you understand your options and negotiate with creditors for you.
Check eligibility Soft search. Won’t affect your score
Free, independent debt help
If your debts feel unmanageable, a free adviser can explain your options and talk to creditors for you. It is confidential and will not affect your credit file.
-
MoneyHelper
Free, impartial money and debt guidance, backed by government, including a debt advice locator.
-
StepChange
Free, confidential debt advice and managed debt plans, online or over the phone.
-
National Debtline
Free, independent advice on dealing with debts, with fact sheets and sample letters.
-
Citizens Advice
Free help with debt, benefits and housing, in person, by phone or online.
0800 144 8848 (England; Wales 0800 702 2020)
If payments stop: what an unsecured lender can and cannot do
The difference between unsecured and secured borrowing shows up when payments stop. This is the order things happen on an unsecured loan, and what a charge over an asset would change at each stage.
Read more
| Stage | On an unsecured loan | If the loan were secured on an asset |
|---|---|---|
| One payment missed | The lender contacts you and reports the missed payment to the credit reference agencies. It has no claim over anything you own. | The same reporting, but the pledged asset is exposed from the first arrears. |
| Arrears reach two payments | You must be sent a notice of sums in arrears under the Consumer Credit Act 1974, with the FCA arrears information sheet. | The same notice is due, and the lender can begin preparing to take the asset back. |
| Default notice served | You get at least 14 days to put the account right before the lender can end the agreement or demand the full balance. | The same 14 days, but the notice is also the step the lender must take before enforcing its security. |
| Account defaults | The debt can be passed or sold to a collections agency, and a default is recorded against you. | The lender can move to repossess and sell the asset. If the sale does not clear the balance, you still owe the shortfall. |
| Court action | The lender can apply for a county court judgment. Even then there is no automatic right to take your property. | Possession of the asset is normally the route instead, so a judgment against you may never be needed. |
| After a judgment | Enforcement can follow: an attachment of earnings order, or a charging order over a property you own, which turns the debt into a secured one. | The security already exists, so no charging order is needed. |
PaydayUK is a credit broker and does not arrange secured loans; the right-hand column is there for contrast only. Steps and timings vary between lenders, and the notices listed are the minimum a regulated agreement requires. Contact your lender before any of this starts.
What does an unsecured loan protect, and what doesn't it?
An unsecured loan protects your home and car, but it doesn't protect you from the consequences of missing payments. No asset is pledged against the agreement, which is a real protection. It's just narrower than many people assume.
Read more
Your home and car aren't attached to the agreement.
Your home isn't at risk in the way it would be with a mortgage or a secured loan.
Your car isn't pledged, unlike a logbook loan where ownership transfers to the lender.
You keep the right to settle early, and to complain if the lender gets something wrong.
The debt is still legally owed, and missing payments has consequences.
Missed payments are reported to credit reference agencies and can make future borrowing harder.
A lender may pursue the debt through the courts, and a county court judgment (CCJ) has consequences of its own.
A lender may pass the debt to a collections agency.
If your agreement has a guarantor, they're liable if you don't pay. Being unsecured doesn't change that.
Unsecured lending is usually priced higher than secured lending.
With no asset to fall back on, the lender relies more heavily on affordability when making its decision. Your interest rate is set by the lender and based on your personal circumstances.
Unsecured is genuinely safer than pledging something you can't afford to lose. Missed payments still carry real consequences, so make sure the repayments fit your budget before you apply.
What are the alternatives to unsecured loans in the UK?
An unsecured loan is not the right solution for everyone. Before you apply, consider whether one of these alternatives might work better for your situation:
Read more
Credit Unions: These member-owned organisations often offer lower rates than commercial lenders. Find your local credit union at findyourcreditunion.co.uk.
Family or Friends: Borrowing from people you know can be interest-free, but make sure to agree clear repayment terms to protect the relationship.
Payment Plans: If you are struggling with a specific bill, contact the company directly. Many utility providers, councils, and other creditors offer payment arrangements.
Free Debt Advice: If you are borrowing to cover existing debts, a free debt charity may find a better way. The free debt help above lists who to contact.
Only borrow if you are confident you can afford the repayments. If you are unsure, take time to work through your budget first.
We've helped out thousands of people...
Rated 4.8 / 5 • 8,121 reviews
Showing our 4 & 5 star reviews
 Read our reviews on Trustpilot

Unsecured loan amounts and terms
Check eligibility Soft search. Won’t affect your score
Representative 91% APR.
Loan guides
These guides will help you find out more about the different types of loan and lenders available.
-
Secured loans against your car: critical warnings and safer alternatives.
-
Find out why no credit check loans don’t exist in the UK and how lenders assess affordability. See the legitimate options if you have bad credit or no credit history.
-
Doorstep loans are still available in some areas, but they're expensive. Find out how home credit works, how to check a lender and what to try first.


Frequently asked questions about unsecured loans
What is an unsecured loan in simple terms?
An unsecured loan is money you borrow without using your home, car or other assets as security. The lender decides based on your income and ability to repay, not on what you own. If you can't repay, the lender can't automatically take your property, but it can still pursue the debt through the courts.
How much can I borrow with an unsecured loan?
You can borrow from £50 to £5,000 with an unsecured loan through Payday UK, repaid over 3 to 36 months. The amount and term a lender offers depend on your circumstances. You can apply online at any time, and if you accept an offer, the money can often arrive the same day.
Should I use an unsecured loan to clear other debts?
An unsecured loan can clear several debts with one monthly payment and a fixed end date, but it only helps if it costs less overall.
It’s essential to check the interest rates and terms of the debts you’re consolidating to ensure you’re not paying more by spreading them over a more extended period.
What is the difference between an unsecured loan and a payday loan?
Unsecured loans and payday loans are both types of borrowing that do not require collateral. Payday loans are usually smaller amounts repaid over a short period. Unsecured personal loans can be larger, with longer terms. Lenders on our panel offer both.
Can I repay my unsecured loan early?
You can repay early at any time and pay less interest. No early repayment charge applies to loans arranged through us. Ask the lender for a settlement figure first. It can include up to 28 days' extra interest. Agreements over a year can add a little more.
What does unsecured loan mean for my property?
It means your home or car is not automatically at risk if you struggle with repayments. Unlike a secured loan or mortgage, the lender has no direct claim over your assets. However, if you default and the lender takes court action, a charging order could eventually be placed on your property. Always ensure you can afford repayments before borrowing.
What credit score do I need for an unsecured loan?
There is no minimum credit score required to apply through Payday UK. Our panel includes lenders who specialise in helping people with various credit histories. Lenders focus on your current ability to afford repayments, not just your past credit behaviour.
