Trusted by 3 million UK customers
£200 loans with an instant decision quote
£200 to cover a bill that will not wait, with the total cost shown before you agree.
What happens after I click?
- You complete one short, secure form.
- A soft search checks your eligibility. Your credit score isn't affected.
- No one will call you.
- If accepted, you see your offer and choose whether to accept.
- We do not charge you a fee for using PaydayUK.
-
4,500+
applications every daySee the footnote substantiating this figure
-
Quick
same day payout available
Excellent
4.8 out of 5 · based on 8,113 reviews
Representative example: Amount of credit: £500 for 6 months at £100.22 per month (final payment £100.21). Total amount repayable of £601.31 Interest: £101.31 Interest rate: 66.49% pa (fixed). Representative 91% APR. Rates between 9.3% APR and maximum 1292.1% APR - your no-obligation quote and APR will be based on your personal circumstances. Credit broker, not a lender. Payday UK (Payday Loans Ltd) is an appointed representative of Flux Funding Limited, which is authorised and regulated by the FCA (FRN 806333).
200 pound loans
Can I get a £200 loan online with Payday UK?
You can apply for a £200 loan online at any time. Payday UK is a credit broker, not a lender. One application reaches a panel of lenders, and each one decides for itself.
Read more
Payday UK can also help you find payday loans from £50 to £5,000.
At £200 the need is usually one specific bill. Typical examples are a vet visit, a washing machine repair, new tyres after a failed MOT, or school uniform.
Lenders usually spread £200 over 3 to 6 months. Some offer longer, but on a balance this size a longer term mostly adds interest.
Check eligibility Soft search. Won’t affect your score
Apply now
Enter an amount in pounds, from £50 to £5,000.
Will I be approved?
We know you need your money as soon as possible. Check where you stand in 3 minutes with a soft search that leaves no mark other lenders can see.
Check eligibility Soft search. Won’t affect your score
How much does a £200 loan cost?
What you repay on a £200 loan depends on the rate the lender offers you and how many months you take to repay. Payday UK shows the total repayable on every offer before you agree.
Read more
Rates across the panel run from 9.3% to 1,292.1% APR, with a representative APR of 91%. Your rate depends on the lender and your circumstances.
Whilst the APR figure appears high, it’s important to understand that APR is an annualised rate. For short-term loans lasting just a few months, the actual interest paid is much lower than the APR percentage might suggest. See the representative example on this page for what a loan could cost.
Representative example: Amount of credit: £200 for 6 months at £40.09 per month (final payment £40.07). Total amount repayable of £240.52 Interest: £40.52 Interest rate: 66.49% pa (fixed). Payday UK is a registered trading name of Payday Loans Ltd, who are an appointed representative of Flux Funding Limited, who are a credit broker, not a lender. Registered in England and Wales (Company number 12430457 / FRN 921539).
What should I consider before applying?
Before you apply for a £200 loan, check that you need to borrow, that the repayments fit your budget, and that no cheaper option would cover the cost.
£200 is easy to borrow and easy to borrow again, so ask yourself these questions first:
Read more
Do you genuinely need to borrow money? Not every unexpected cost needs immediate borrowing. If this is something that could wait a few weeks until you’re paid, waiting might save you the cost of interest entirely. Be honest about whether speed is truly necessary.
Can you afford the repayments? Look at your monthly income and list all your regular expenses including rent or mortgage, bills, food, transport, and any existing loan payments. The loan repayment needs to fit comfortably within your disposable income with some buffer for unexpected costs.
Do you understand the total cost? Make sure you know exactly how much you’ll repay in total, not just the monthly amount. The representative example on this page shows what a loan could cost. Is that acceptable to you for the convenience and speed?
Free, independent debt help
If £200 goes missing most months, talk to a free debt adviser before you borrow. The advice is confidential and leaves no mark on your credit file.
-
MoneyHelper
Free, impartial money and debt guidance, backed by government, including a debt advice locator.
-
StepChange
Free, confidential debt advice and managed debt plans, online or over the phone.
-
National Debtline
Free, independent advice on dealing with debts, with fact sheets and sample letters.
-
Citizens Advice
Free help with debt, benefits and housing, in person, by phone or online.
0800 144 8848 (England; Wales 0800 702 2020)
If you're unsure whether borrowing is right for you, our eligibility criteria page explains who lenders can consider.
Covering a £200 bill, with and without borrowing
At this size several routes can cover the whole bill without a credit agreement. What is open to you depends on your circumstances, none of these is an offer, and the provider sets the timing, not PaydayUK.
Read more
| Route | Covers £200 in full | How soon | Main trade-off |
|---|---|---|---|
| Payment plan with the company you owe | Often - a bill this size is commonly split across your next two or three payments | Same day to a few days, once you ask | You have to ask, ideally before the due date, and not every company agrees |
| Council welfare assistance or a supplier hardship fund | Sometimes - schemes usually cover essentials such as energy, food or a replacement appliance | Days to weeks, depending on the scheme and how urgent your situation is | Means-tested, differs by council and supplier, and usually limited to one award in a period |
| Salary advance or a hardship fund at work | Often covers an amount this size in full | Tied to your employer's payroll cycle | Not offered everywhere, and it reduces your next payslip |
| Credit union loan | Yes - £200 is within range for most credit unions | Days rather than minutes, and you may need to join first | Membership usually depends on where you live, work or worship |
| An arranged overdraft you already hold | Yes, if your arranged limit reaches £200 | Immediate, if the facility is already in place | Interest accrues for each day you stay overdrawn unless your account has an interest-free buffer, and the bank can reduce or withdraw the limit |
| A credit card you already have | Yes, if you have £200 of unused limit | Immediate for a purchase | No interest if you clear the balance in full by the due date; interest runs from then on, and cash withdrawals are charged from day one |
| A £200 loan from our panel | Yes - £200 sits near the bottom of the £50 to £5,000 range the panel lends over | The lender runs its own checks and sets the timing | A credit agreement with interest, and the repayment history is recorded on your credit file |
Not an exhaustive list, and not advice. The free, independent debt advice services listed above will talk any of these through with you before you borrow.
What if my circumstances change mid-term?
If your circumstances change while you're repaying a £200 loan, contact the lender as soon as you see a problem coming, as it can often move a payment date or agree an arrangement.
Read more
Plans made when you take a loan do not always survive the months that follow. Hours get cut, a benefit is reassessed, a bill lands that was not in the budget. None of that is unusual and none of it has to become a default.
The lender has to treat you fairly if you are in difficulty. It can do far more before a payment fails than after, so call before the due date.
Check eligibility Soft search. Won’t affect your score
How it works
We know you need your money as soon as possible. That's why we have designed our website to be fast and simple.
-
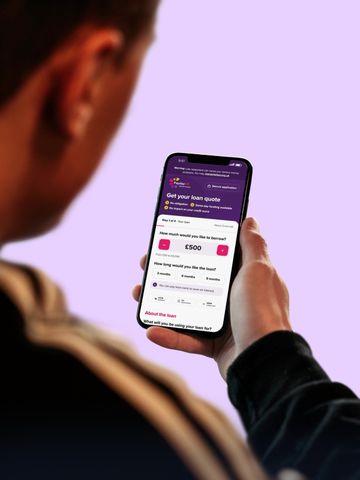
Apply online
Fill out our short, secure form and search a panel of FCA-regulated lenders to see the offers available to you.
-
Check your offer
Once you have your offer from the lender, you can review the offer and get your cash.
-
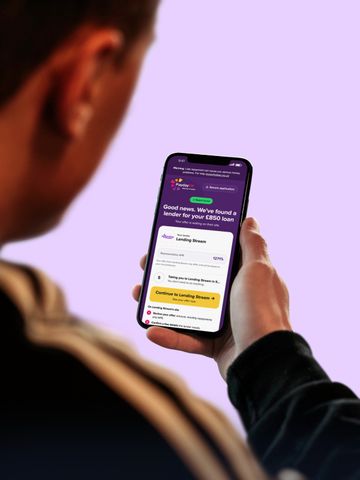
Get your money
Once accepted, your money can often be paid into your account the same day.
We've helped out thousands of people...
Rated 4.8 / 5 • 8,113 reviews
Showing our 4 & 5 star reviews
 Read our reviews on Trustpilot

£200 loan amounts and terms
Check eligibility Soft search. Won’t affect your score
Representative 91% APR.
Loan guides
These guides will help you find out more about the different types of loan and lenders available.
-
Need cash fast? Explore quick funding options for financial emergencies.
-
Understand Annual Percentage Rate and how it affects your loan costs.
-
Explore government support, interest-free advances and responsible borrowing options if you're receiving benefits.


More questions? Your questions answered
How quickly can I get a £200 loan?
Many lenders can send a £200 loan the same day once they approve your application. Exact timing depends first on the lender's own checks and then on how quickly your bank processes the incoming payment. The lender can tell you its usual payout times. Signing the agreement promptly, once you're happy with it, avoids any delay on your side.
Can I borrow £200 with bad credit?
Approval is never guaranteed, but you can apply to borrow £200 with bad credit through Payday UK. A past mistake doesn't rule you out on its own. Lenders on the panel look at your current income and outgoings as well as your credit history, so what matters most is whether the repayments fit your budget now.
Can I repay my £200 loan early?
You can repay early at any time and pay less interest. No early repayment charge applies to loans arranged through us. Ask the lender for a settlement figure first. It can include up to 28 days' extra interest.
How many times can a lender attempt a payment?
A lender collecting your £200 loan by continuous payment authority can make two failed attempts at a payment, then it must stop and contact you. You can withdraw a continuous payment authority at any time by telling your bank. That stops the payments being taken, but it doesn't cancel what you owe.
What if I want to complain about the lender?
Complain to the lender first, in writing if you can. It has eight weeks to give you a final response. If that does not settle it, you have six months to take the complaint to the Financial Ombudsman Service, which is free to use and can order the lender to put things right.
