Trusted by 3 million UK customers
£800 loans with an instant decision quote
£800 for a larger unexpected cost, repaid monthly over a term you pick.
What happens after I click?
- You complete one short, secure form.
- A soft search checks your eligibility. Your credit score isn't affected.
- No one will call you.
- If accepted, you see your offer and choose whether to accept.
- We do not charge you a fee for using PaydayUK.
-
4,500+
applications every daySee the footnote substantiating this figure
-
Quick
same day payout available
Excellent
4.8 out of 5 · based on 8,057 reviews
Representative example: Amount of credit: £500 for 6 months at £100.22 per month (final payment £100.21). Total amount repayable of £601.31 Interest: £101.31 Interest rate: 66.49% pa (fixed). Representative 91% APR. Rates between 9.3% APR and maximum 1292.1% APR - your no-obligation quote and APR will be based on your personal circumstances. Credit broker, not a lender. Payday UK (Payday Loans Ltd) is an appointed representative of Flux Funding Limited, which is authorised and regulated by the FCA (FRN 806333).
800 pound loans
Can I get an £800 loan online with Payday UK?
Payday UK works with a large panel who offer £800 payday loans. Complete our quick form and we will do the rest for you.
If you need an £800 loan quickly, our application process is quick, simple and secure. There is no additional paperwork, and you’ll get an instant decision quote. You must be aged 18 or over and a permanent resident of the UK.
Payday UK is a credit broker, not a lender. We search a panel of FCA-authorised lenders and show you which may consider you. Checking costs you nothing and uses a soft credit check. FCA-authorised lenders cannot offer genuine no credit check loans, because every lender must check you can afford the repayments.
Check eligibility Soft search. Won’t affect your score
£800 loans explained
What changes when you borrow £800?
£800 usually pays for something that can’t wait, like a major car repair, a replacement boiler or moving costs. Sometimes it is several bills landing at once.
Read more
Nothing is secured against it, so your property is not at risk. But missed payments still cost you in fees and mark your credit file for six years.
At £800, two things change. Lenders scrutinise affordability more closely, and the term offered is usually longer, spreading the amount over more months to keep each payment manageable.
The trade-off at this amount
A longer term makes the monthly payment affordable and increases the total interest. A shorter term does the reverse. At £800 that gap is real money, so it's worth working out both totals rather than only comparing monthly figures.
Terms across our panel run from 3 to 36 months. Choose the one you could still meet in a month where something else goes wrong.
£800 repaid over a short term is a significant monthly commitment, and there are cheaper ways to borrow if you have the time or the eligibility.
Check eligibility Soft search. Won’t affect your score
Apply now
Enter an amount in pounds, from £50 to £5,000.
Will I be approved?
We know you need your money as soon as possible. Check where you stand in 3 minutes with a soft search that leaves no mark other lenders can see.
Check eligibility Soft search. Won’t affect your score
Cheaper ways to borrow £800
Cheaper credit often exists if you can wait or your credit file is reasonable. Our guide to alternatives to payday loans compares the options.
How does an £800 loan work through Payday UK?
One application searches the panel. We show you the lenders that may consider you, you choose an offer, and you complete it with that lender - the credit agreement is between the two of you.
One soft search, not several hard ones. Several hard searches in a short period is itself a signal that makes the next lender more cautious.
No fee to you. The lender pays us a commission if you take a loan. A broker asking you for money upfront is not a broker worth using.
No obligation. You can look at an offer and walk away.
FCA-authorised lenders only. Check any lender on the FCA Register.
Read more
We are paid by the lender, which is worth knowing when you read any broker’s recommendation - including ours. Our guide to direct lenders and brokers explains how that works across the market.
What does an £800 loan cost?
The cost of an £800 loan depends on the lender, the term and your circumstances, and you will see the total repayable before you agree to anything.
Read more
Why the APR is not the number to compare
Rates on our panel run from 9.3% APR up to a maximum of 1292.1% APR. APR expresses cost as an annual rate, which suits a mortgage and distorts a loan meant to last months.
Compare the total repayable in pounds and the monthly payment. Those are the two numbers you will actually live with. Our guide to APR explained shows why the headline percentage misleads at short terms.
Who can apply for an £800 loan?
Lenders on our panel have loan eligibility criteria. You will be considered if you:
Read more
are at least 18 years old
live in the UK
have a UK bank account and a debit card
have a regular, verifiable income
can afford the repayments alongside your existing commitments
At £800 the affordability assessment carries more weight than it does for small loans. Lenders will look at what comes in, what goes out and what you already owe. Being declined is not a judgement on you. It usually means the numbers did not leave enough room, which is the check doing its job.
Can I get an £800 loan with bad credit?
You can still apply for an £800 loan with bad credit through Payday UK. Our panel of direct lenders provides short term loans to people who struggle to borrow elsewhere.
Lenders who specialise in bad credit weight your current affordability more heavily than your history. However, active defaults, recent county court judgments or an ongoing debt arrangement make acceptance less likely than if you were applying for a £100 loan or similar.
Each lender sets its own rules for borrowing with bad credit, and most focus on what you can afford now rather than what went wrong before.
What should I think about before I apply?
At £800 the monthly commitment is real. These questions are worth answering honestly before you apply, not after.
Do you need the full £800? Borrowing less costs less across every month of the term. If £600 fixes it, borrow £600.
What is the total? Write down the total repayable and compare it against what you are solving. Sometimes it changes the decision.
Can you meet the payment on a bad month? Not an average month - a bad one. That is the month that decides whether this works.
Have you checked the cheaper routes above? A credit union at 42.6% APR is a different proposition from short-term credit, if you can wait.
Is this borrowing to repay borrowing? If so, stop and speak to a free debt adviser first. Another loan makes that worse rather than better.
Free, independent debt help
At £800 the repayments run for months, so talk it through first if money is tight. Free advice is confidential and does not affect your credit file.
-
MoneyHelper
Free, impartial money and debt guidance, backed by government, including a debt advice locator.
-
StepChange
Free, confidential debt advice and managed debt plans, online or over the phone.
-
National Debtline
Free, independent advice on dealing with debts, with fact sheets and sample letters.
-
Citizens Advice
Free help with debt, benefits and housing, in person, by phone or online.
0800 144 8848 (England; Wales 0800 702 2020)
If you're unsure whether borrowing is right for you, our eligibility criteria page explains who lenders can consider.
How does Payday UK protect me?
We are registered with the Information Commissioner under ZA654345. Our registered office is Payday Loans Ltd, The Charter Building, Charter Place, Uxbridge, UB8 1JG.
A soft search, always. Checking with us leaves no footprint other lenders can see.
No upfront fees. We never ask you to pay to borrow.
Your data is not sold on. It goes to panel lenders to find you an offer, and no further.
A real complaints route. Acknowledged within 5 working days, resolved within 8 weeks where we can, and referable free of charge to the Financial Ombudsman Service within 6 months of our final response.
Read more
Call 0800 302 9409 - free from UK landlines and mobiles. See our complaints procedure and our responsible lending commitments for the detail.
Ready to check your eligibility?
Checking takes about a minute, uses a soft search, and commits you to nothing. You will see what our panel can offer before deciding.
Comparing amounts? See £500 loans, £700 loans, £900 loans and £1000 loans. To spread the cost further, 12 month loans and instalment loans are the longer-term options.
You have fourteen days to change your mind
Almost every regulated credit agreement gives you 14 days to withdraw. The 14 days start the day after the agreement is made. You do not have to give a reason.
Read more
Withdrawing does not cancel the debt. You repay what you borrowed, plus interest for the days you held it. The lender must tell you the amount.
Check eligibility Soft search. Won’t affect your score
What the money actually arriving looks like
Once a lender approves you, it usually sends the money by Faster Payment. It often arrives within minutes. Timing still depends on your bank, the time of day and any extra checks.
Read more
An application approved late on a Friday can sit until the next working day. If the £800 is covering something with a deadline, build in more time than the fastest case, and check the payment date the lender has set before you accept rather than after.
Check eligibility Soft search. Won’t affect your score
What an £800 loan does to your credit file
The agreement is recorded for its whole life and for six years after it closes. Each month the lender reports whether the payment was made, so a loan repaid to schedule leaves a run of positive entries behind it.
Read more
The reverse is equally durable. A missed payment stays visible for six years and affects applications long after the balance is cleared. That asymmetry is the strongest argument for choosing a payment you are confident about rather than the largest one you could just about manage.
Check eligibility Soft search. Won’t affect your score
How it works
We know you need your money as soon as possible. That's why we have designed our website to be fast and simple.
-
Apply online
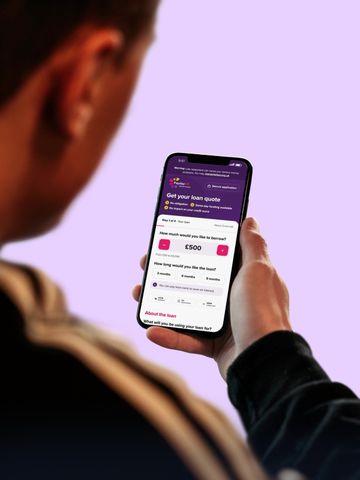
Fill out our short, secure form and search a panel of FCA-regulated lenders to see the offers available to you.
-
Check your offer
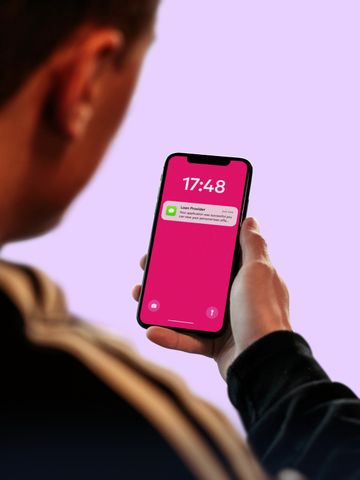
Once you have your offer from the lender, you can review the offer and get your cash.
-
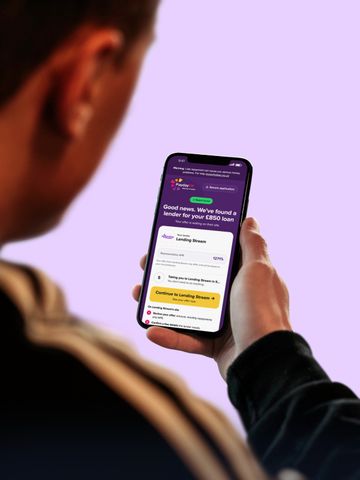
Get your money
Once accepted, your money can often be paid into your account the same day.
We've helped out thousands of people...
Rated 4.8 / 5 • 8,057 reviews
Showing our 4 & 5 star reviews
 Read our reviews on Trustpilot

£800 loan amounts and terms
Check eligibility Soft search. Won’t affect your score
Representative 91% APR.
Loan guides
These guides will help you find out more about the different types of loan and lenders available.
-
What to compare beyond the APR, from the total you'll repay to what happens if a payment fails.
-
Understand Annual Percentage Rate and how it affects your loan costs.
-
Avoid scams and find FCA-authorised lenders. Learn the safe way to apply online.


More questions? Your questions answered
How soon do I have to pay my £800 loan back?
You pay your £800 loan back over the term you agree with the lender, usually several months rather than in one payment. Smaller loans tend to have shorter terms, while larger amounts are spread further. Don’t overstretch yourself, because every repayment needs to be made on time, so be realistic about your monthly budget.
Can Payday UK find me an £800 loan quickly?
You usually see within minutes whether a lender on our panel may offer you £800. The lender runs a full credit check only if you go ahead. Read our guide to how to get a quick loan.
How much will an £800 loan cost me in total?
The total cost of an £800 loan depends on the rate you are offered and the term you choose, so read the total repayable on your own agreement. Rates across our panel run from 9.3% APR to a maximum of 1292.1% APR, depending on your personal circumstances. A longer term lowers the monthly payment but raises the total.
Can I borrow £800 if I have never had credit before?
You may still get an £800 loan with no credit history, because a thin credit file is not the same as a bad one. With less to go on, lenders lean harder on your income and outgoings. Some lenders on our panel are used to applicants with little history, and a decline usually reflects a lack of evidence rather than anything about you.
What if I miss a payment on an £800 loan?
Tell the lender before the payment is due rather than after. It has to treat you fairly if you are in difficulty, and can often move the date or set up a plan. Interest can keep running, and missed payments are reported to credit reference agencies.
Why would an £800 application be declined?
Lenders have to check that repayments are affordable for you, not just that you can be sold a loan. They look at income, regular outgoings and existing commitments. That check protects you from an agreement you cannot keep up, and it is the reason an application can be declined even when nothing is wrong with your credit file.
