Trusted by 3 million UK customers
£50 loan with an instant decision quote
Making it happen.
A £50 loan for the smallest gap - the days between now and payday, borrowed properly.
-
3 million
customers helped
-
4,500+
applications a daySee the footnote substantiating this figure
-
Excellent
4.8 out of 5 · 8,132 reviews on
What happens after I click?
- You complete one short, secure form.
- A soft search checks your eligibility. Your credit score isn't affected.
- No one will call you.
- If accepted, you see your offer and choose whether to accept.
- We do not charge you a fee for using PaydayUK.
-
4,500+
applications every daySee the footnote substantiating this figure
-
Quick
same-day payout if approved
- CCTA Member
- ico. Registered
- GDPR Compliant
Excellent
4.8 out of 5 · based on 8,132 reviews
- CCTA Member
- ico. Registered
- GDPR Compliant
Representative example: Amount of credit: £500 for 6 months at £100.22 per month (final payment £100.21). Total amount repayable of £601.31 Interest: £101.31 Interest rate: 66.49% pa (fixed). Representative 91% APR. Rates between 9.3% APR and maximum 1292.1% APR - your no-obligation quote and APR will be based on your personal circumstances. Credit broker, not a lender. Payday UK (Payday Loans Ltd) is an appointed representative of Flux Funding Limited, which is authorised and regulated by the FCA (FRN 806333).
50 pound loans
Can I get a £50 loan online?
You can apply for a £50 loan online through Payday UK in about a minute, though approval is never guaranteed. The first check is a soft search, so it leaves no mark other lenders can see.
Payday UK is a credit broker, not a lender. We search a panel of FCA-authorised lenders and show you which of them may consider you. The lender you choose makes the final decision and sets the terms.
Sometimes you need a small loan to get you through to payday, even if you have a low credit score. A £50 loan is the smallest amount Payday UK can help you find. People usually look for one when they are a few days from payday and short by a small amount they need for an unexpected bill or emergency.
Through Payday UK, you can apply for payday loans ranging from £50 to £5,000.
Check eligibility Soft search. Won’t affect your score
What alternatives are there to borrowing £50?
Interest on a small, short loan can look like a lot next to the amount you borrowed. These options usually cost less, and some cost nothing at all.
Read more
Ask your employer for an advance. Many employers will bring forward part of your wages, and it costs nothing. It is a short conversation, and a common one.
Check your current account. An arranged overdraft of £50 for a few days is often cheaper than a short-term loan. An unarranged one usually is not, so check which you have.
Speak to whoever you owe. Energy suppliers, councils and phone providers all have hardship teams. They can spread a bill or pause it, and asking does not affect your credit file.
Check what you are entitled to. Household Support Fund grants and budgeting loans are money you may not have to repay, or can repay without interest.
For free, independent help with any of these, speak to MoneyHelper - a government-backed service that costs nothing and will not sell you anything. Our guide to emergency money covers these options in more detail.
Apply now
Enter an amount in pounds, from £50 to £5,000.
Will I be approved?
We know you need your money as soon as possible. Check where you stand in 3 minutes with a soft search that leaves no mark other lenders can see.
Check eligibility Soft search. Won’t affect your score
What should I know before borrowing £50?
£50 is the floor on our panel - you cannot ask for less, and several things behave differently down there. This describes how it works. It is not an offer or a quote.
Read more
| What people expect at £50 | What happens at the panel's floor | What to do |
|---|---|---|
| Asking for less than £50 | £50 is the smallest loan on the panel, so there is no smaller amount to apply for. | If your gap is smaller than that, borrowing is the wrong tool for it - do not borrow up to the floor. |
| Clearing it on payday | The shortest agreement on our panel runs 3 months, so £50 is repaid in instalments rather than in one go. | Check every payment date against your pay dates, not just the first one. |
| Rounding it up to a tidier number | The extra is borrowed on the same terms as the part you actually needed, and at this size rounding up can double the balance you pay interest on. | Apply for the amount you are short, not the nearest round number. |
| Treating it as a one-off | A small amount is the easiest kind to borrow again, and each new agreement starts its own fixed costs over. | If you have needed a small top-up more than once recently, the pattern matters more than this month's £50. |
Payday UK is a credit broker, not a lender. The amount, term and rate available to you are set by the lender.
What does a £50 loan cost?
The cost of a £50 loan depends on the lender, the term and your circumstances, and you will see the total repayable in pounds before you agree to anything. The representative example on this page shows the cost of a typical loan through our panel.
Read more
Why the APR looks so high
APR stands for Annual Percentage Rate. It expresses the cost of credit as if you were borrowing for a whole year. On a loan that lasts a few months, that turns a small sum in pounds into a very large percentage.
Rates across our panel run from 9.3% APR to a maximum of 1292.1% APR. For a short-term loan, the number worth comparing is the total amount you will repay in pounds, not the APR. Our guide to APR explained goes through this in full.
How does Payday UK protect you?
We are registered with the Information Commissioner under ZA654345.
A soft search, always. Checking your eligibility leaves no footprint other lenders can see.
No upfront fees, ever. A genuine broker or lender never asks you to pay before you borrow. Anyone who does is not one.
Your data stays with the panel. We share your details with lenders to find you an offer. We do not sell them on to unrelated marketers.
A real complaints route. If we get something wrong, we acknowledge a complaint within 5 working days. We aim to resolve it within 8 weeks. You can then take it to the Financial Ombudsman Service free of charge.
You can reach us on 0800 302 9409, which is free from UK landlines and mobiles. Full detail is in our complaints procedure and our approach to lending is set out in responsible lending.
What should I check before borrowing £50?
Before you apply for a £50 loan, check the repayment date, the total repayable and whether you could cover the gap without borrowing.
Borrowing £50 can feel like a small decision, but getting it wrong isn't small. A fee or a few days of interest is a big share of £50. A missed payment also shows on your credit file in the same way as one on a £5,000 loan.
Check these things before you apply:
The date the repayment leaves your account, and whether your balance will cover it on that day rather than that week.
The total repayable, not the rate. On a sum this small an APR is a misleading way to read the cost.
Whether the £50 is a gap or a symptom. If it is the third £50 this quarter, the loan is not the problem being solved.
Whether the bill it covers can wait. Many providers will hold a payment for a few days if you ask before it is due.
What happens if the payment fails, and what the lender will do next.
That the lender is authorised. You can check any firm on the Financial Services Register before you give it your details.
None of this is a reason not to borrow £50 if you need it and can repay it. It is the difference between borrowing on purpose and borrowing because it was the quickest button to press.
Ready to check?
You can check if you're eligible for a £50 loan in about a minute, using a soft search that does not commit you to anything. You will be able to compare payday loan offers from lenders on the panel before you decide. If you’re 18 to 25, our guide to loans for young people explains what lenders look for.
If you are not sure a loan is right, that is a reasonable conclusion - go back to the alternatives near the top of this page, or speak to MoneyHelper first. Borrowing you do not need is the expensive kind.
You can also compare other amounts: £100 loans, £200 loans, £300 loans and £500 loans.
Why many lenders won't go as low as £50
Most of what it costs a lender to set up a loan is fixed. The identity checks, the affordability assessment and the paperwork cost much the same whether you're borrowing £50 or £5,000. That's why many lenders set their minimum well above £50.
Read more
It is worth knowing that before you read a decline as a judgement about you. For an amount this small, a credit union or an interest-free Budgeting Advance may serve you better than a commercial lender can.
What a lender must do if you are struggling
If you're struggling to make repayments, a lender legally has to treat you fairly, consider a reasonable repayment arrangement, and it cannot pressure you into borrowing again to cover what you already owe.
Read more
On a £50 loan, those protections matter more than they sound, because the sums involved make it tempting to treat a problem as too small to raise. Tell the lender before a payment fails rather than after. The conversation is easier and the outcome is usually better.
A £50 loan is recorded exactly like a large one
Credit reference agencies do not weight an entry by size. The size of a short term loan makes no difference to how it's recorded. Pay £50 back on time and your file shows a loan repaid on time. Miss a £50 payment and your file shows a missed payment. Either way, it stays there for six years.
Read more
This means that if you have thin credit history, a small loan paid off on time is real proof you can repay. But on the flip side, an amount that feels too small to worry about can still do real damage if you forget it.
Check eligibility Soft search. Won’t affect your score
How £50 loans work through Payday UK
Here at Payday UK, we make finding your £50 loan as straightforward as possible to help smooth out life’s road bumps.
-
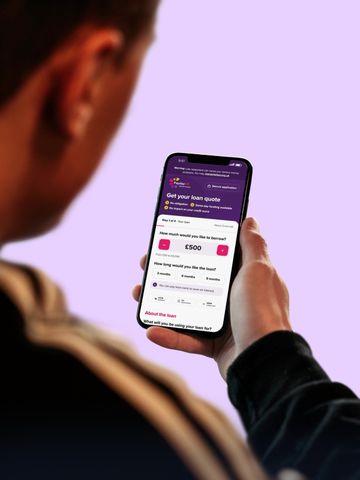
Apply online
Fill out our short, secure form and search a panel of FCA-authorised lenders and brokers to see the offers available to you.
-
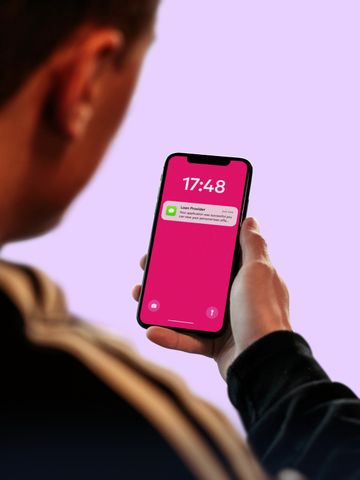
Check your offer
Lenders check what you can afford. Compare the total repayable before you accept.
-
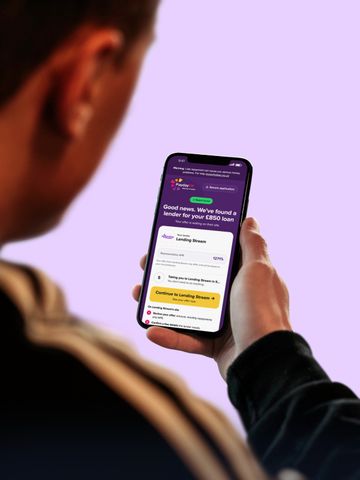
Get your money
If you’re approved and accept, the lender can often pay the same day.
We've helped out thousands of people...
Rated 4.8 / 5 • 8,132 reviews
Showing our 4 & 5 star reviews
 Read our reviews on Trustpilot

£50 loan amounts and terms
Check eligibility Soft search. Won’t affect your score
Representative 91% APR.
Loan guides
These guides will help you find out more about the different types of loan and lenders available.
-
Can a young person get a loan with no credit history? What lenders check, how to build credit from nothing, and the cheaper options to try first.
-
Personal loans for students: types, criteria, and when they're worth it.
-
Doorstep loans are still available in some areas, but they're expensive. Find out how home credit works, how to check a lender and what to try first.


More questions? Your questions answered
Are £50 loans available with bad credit?
£50 loans are available with bad credit, though approval is never guaranteed. Many lenders on the Payday UK panel look at your current income and outgoings, not only your credit history. Checking your eligibility uses a soft search, so it leaves no mark other lenders can see.
How quickly can I get a £50 loan?
The application is online and takes a few minutes, and lenders on our panel give a decision straight away. Once you accept an offer, your money can often be paid into your account the same day, though the lender decides when it is sent.
Is £50 too small for a lender to bother with?
£50 is not too small for every lender, but some set their minimum higher, so you will have fewer lenders to choose from than at larger amounts. Across the Payday UK panel, amounts start at £50. If nothing comes back, a credit union or an interest-free Budgeting Advance often suits a sum this size better.
What will a £50 loan actually cost?
What a £50 loan costs depends on the lender and the term, so compare the total repayable in pounds rather than the APR. The lender shows you that total before you agree.
Is there a cheaper way to cover £50?
There is often a cheaper way to cover £50 than a loan. A credit union, an interest-free overdraft buffer, a Universal Credit Budgeting Advance or a few days' grace from the company you owe will usually cost less. If the £50 is for an essential bill, call that provider first, as most will spread a payment.
Can I pay a £50 loan back early?
You can repay early at any time and pay less interest. No early repayment charge applies to loans arranged through us. Ask the lender for a settlement figure first. It can include up to 28 days' extra interest.
What if I cannot repay £50 on the due date?
If you cannot repay £50 on the due date, tell the lender before the payment is due. It must treat you fairly and can often move the date or set up a plan. Interest can keep running, and missed payments are reported.
Can the lender try again if the payment bounces?
No. If a lender collects by continuous payment authority it may make two attempts at a payment, and after two failures it must stop and contact you. You can also withdraw a continuous payment authority at any time by telling your bank, though that does not cancel what you owe.
