Trusted by 3 million UK customers
3-month loans
Three months to repay - the shortest term we offer, and usually the cheapest overall.
What happens after I click?
- You complete one short, secure form.
- A soft search checks your eligibility. Your credit score isn't affected.
- No one will call you.
- If accepted, you see your offer and choose whether to accept.
- We do not charge you a fee for using PaydayUK.
-
4,500+
applications every daySee the footnote substantiating this figure
-
Quick
same day payout available
Excellent
4.8 out of 5 · based on 8,088 reviews
Representative example: Amount of credit: £500 for 6 months at £100.22 per month (final payment £100.21). Total amount repayable of £601.31 Interest: £101.31 Interest rate: 66.49% pa (fixed). Representative 91% APR. Rates between 9.3% APR and maximum 1292.1% APR - your no-obligation quote and APR will be based on your personal circumstances. Credit broker, not a lender. Payday UK (Payday Loans Ltd) is an appointed representative of Flux Funding Limited, which is authorised and regulated by the FCA (FRN 806333).
3 month loans online
Can I get a 3-month payday loan online?
You can apply for a 3 month payday loan online through Payday UK using one short form.
Sometimes you need a little extra cash to cover an unexpected expense but don’t want to repay the full amount right away. A 3 month loan lets you borrow what you need and spread your repayments over three manageable monthly instalments. It’s one of the most popular types of short term loans in the UK.
Read more
The amount and term that suit you depend on your circumstances, but 3 month loans are usually taken for small loan amounts. You can borrow from £50.
Payday UK is a credit broker, not a lender. This means we search our panel of FCA-regulated lenders to find options that match your circumstances. Lenders start with a soft credit check, so you can see if you qualify without affecting your credit score.
Check eligibility Soft search. Won’t affect your score
three month loans explained
What is a 3-month loan?
A 3 month loan is a type of short term loan where you repay what you’ve borrowed over three monthly instalments. Instead of paying everything back in one lump sum , as you would with traditional payday loans, you split the cost into smaller, more manageable chunks.
Read more
This type of loan sits between very short-term options and longer personal loans. It’s designed for people who need money soon but want a bit more breathing room when it comes to paying the money back. The three month timeframe keeps your borrowing short while reducing the pressure on your monthly budget. If speed is your priority, it’s worth knowing how to get a quick loan first.
These loans work well for one-off expenses you didn’t see coming. A broken washing machine, an MOT failure, or an unexpected vet bill can all throw your budget off track. A 3 month loan gives you the funds to handle the problem now, then spread the repayment across the next few pay days.
Check eligibility Soft search. Won’t affect your score
Apply now
Enter an amount in pounds, from £50 to £5,000.
Will I be approved?
We know you need your money as soon as possible. Check where you stand in 3 minutes with a soft search that leaves no mark other lenders can see.
Check eligibility Soft search. Won’t affect your score
How do I get a 3-month loan through Payday UK?
You get a 3 month loan through Payday UK by filling in one online form, seeing which lenders on the panel can help, then finishing your application with the lender you choose.
Here’s what happens at each step:
Step 1: Tell us what you need. Use our online form to enter how much you want to borrow and confirm you’d like to repay over three months. The form takes about two minutes to complete.
Step 2: The lenders in our panel run a soft credit check to see if you might be eligible. A soft search doesn’t leave a mark on your credit file that other lenders can see, and it won’t affect your credit score.
Step 3: See your options. If lenders in our panel can help, you’ll see the offers available to you. Each offer shows the interest rate, monthly repayment amount, and total cost. You’re under no obligation to accept any offer.
Step 4: Choose and complete. If you find an offer that works for you, click through to the lender’s site to complete your application. The lender will then run a full credit check before making a final decision.
Step 5: Receive your funds. If the lender approves your application, they’ll transfer the money to your bank account. Many of our panel lenders offer same-day transfers, so you could have the cash within hours.
Throughout this process, Payday UK never charges you any fees. Our service is completely free to use. We only get paid by lenders when you successfully take out a loan, and this never affects what you pay.
With only three payments, you know exactly what leaves your account each month and the date the debt ends.
Check eligibility Soft search. Won’t affect your score
How much does a 3-month loan cost?
A 3 month loan has a higher interest rate than a traditional bank loan, because it’s built for quick access over a short term. The exact cost depends on the lender, how much you borrow and your circumstances.
Read more
Rates between 9.3% APR and maximum 1,292.1% APR - your no-obligation quote and APR will be based on your personal circumstances. It helps to understand how APR works before you compare offers.
Shorter loan terms like three months often mean you pay less interest overall compared to 6 month loans or 12 month loans. That’s because the money is with you for less time. However, your monthly payments will be higher than they would be with a longer term. It’s about finding the balance that works for your budget.
Check eligibility Soft search. Won’t affect your score
Who can apply for a 3-month loan?
Lenders in our panel have their own specific criteria, but most will need you to meet these basic loan eligibility requirements:
Read more
Be at least 18 years old
Be a UK resident
Have a UK bank account and debit card
Have a regular source of income
Have a valid email address and mobile phone number
Your income can come from employment, self-employment, and some lenders on the panel offer loans for people on benefits. Each lender sets its own minimum income. What matters most is that you can afford the repayments alongside your existing bills and commitments.
Many people worry that past credit problems will stop them getting approved. While lenders do check your credit history, it’s not the only thing they look at. Our panel includes lenders who specialise in helping people with less than perfect credit scores. They focus more on your current affordability than what happened years ago.
If you’ve been turned down elsewhere, a 3 month loan through PaydayUK might still be possible. Because we search multiple lenders with one application, you have more chances of finding one willing to help. Before you apply again, it’s worth reading how to get a loan with bad credit.
Why use a broker like Payday UK?
Using a broker like Payday UK for a 3 month loan means one application reaches a panel of lenders, instead of you applying to each lender one by one. It lets you compare payday loans side by side. Here’s why the broker route often makes more sense:
Read more
More options, one application. Instead of filling out forms with several different lenders, you complete one application with us. We then search our entire panel to find lenders who might be able to help. This saves you time and hassle.
Soft credit check protection. Every time you apply directly to a lender, they typically run a hard credit check. Multiple hard checks in a short period can damage your credit score. FCA-regulated lenders don’t offer genuine no credit check loans, so the check can’t be skipped, but you can choose when it happens. With Payday UK, lenders start with a soft check that doesn’t affect your score. Hard checks only happen once you’ve chosen a lender and decided to proceed.
No fees from us. Payday UK never charges you for using our service. We’re paid by lenders when loans complete, and this commission doesn’t affect what you pay. The loan costs the same whether you find the lender directly or through us.
More lenders consider your application. Different lenders have different criteria. If one lender in our panel can’t help, another might be able to. This means more lenders consider your application than if you applied to just one.
FCA protection across the board. Every lender in our panel is authorised and regulated by the Financial Conduct Authority. This means they must follow strict rules about responsible lending, clear pricing, and fair treatment. You’re protected no matter which lender you choose.
Why choose a 3-month repayment term?
Choosing a 3 month repayment term means you pay less interest overall and you’re done with the debt sooner. The catch is that each payment is bigger, so it needs to sit comfortably in your budget.
Read more
How long you take to repay changes both what you pay each month and what the loan costs you in total. Three months is about as short as it gets, and that comes with a few upsides:
Clear the debt quickly. Three months is about 13 weeks. The debt is gone soon after you borrow, with no long-term commitment hanging over you.
Pay less interest overall. A 3 month loan will typically cost less in total interest than the same amount borrowed over six or twelve months. The shorter your loan term, the less time interest has to build up.
Stay focused on repayment. A shorter term keeps repayment front of mind. You’re more likely to budget carefully when you know the loan will be cleared soon.
Manageable monthly amounts. While 3 month loans have higher monthly payments than longer terms, they’re designed to be affordable. Lenders must check you can manage the repayments before approving your application.
Of course, three months isn’t right for everyone. If the monthly payments would stretch your budget too thin, a longer term might be better. Lenders on the panel offer terms from 3 to 36 months, so you can choose what works best for your situation. The key is borrowing only what you need and choosing a term you can comfortably afford.
Check eligibility Soft search. Won’t affect your score
What should I consider before applying for a 3-month loan?
Before you apply for a 3 month loan, take a moment to think through a few things:
Can you afford the repayments? Look at your income and regular expenses. Will the monthly repayments fit comfortably, or will they leave you short? If there’s any doubt, borrowing might not be the right choice right now.
Have you explored other options? Could you ask family for help, use savings, or negotiate a payment plan with whoever you owe money to? Sometimes there are cheaper or easier solutions than borrowing.
Is this expense essential? Short-term loans are designed for emergencies and unexpected costs, not for treats or nice-to-haves. Only borrow if you genuinely need to.
Do you understand the costs? Make sure you know exactly how much you’ll repay in total. Our representative APR is 91%, but your actual rate may differ. Check the specific offer before accepting.
What if you can’t repay? Missing payments can make your situation worse. There are fees, it damages your credit score, and the stress can build. Only borrow if you’re confident you can repay on time.
If you’re struggling with debt or money worries, free and confidential help is available. The services listed further down this page can help.
How does Payday UK protect me?
We take your safety seriously. Here’s how we make sure you’re protected:
Regulated lender panel: Every lender in our panel is FCA-authorised and must follow responsible lending rules. This includes checking you can afford repayments before approving a loan.
Data protection: We’re registered with the Information Commissioner’s Office (ICO registration ZA654345). Your personal information is handled securely and only used for the purposes you’ve agreed to.
Soft credit checks: Your initial eligibility check won’t affect your credit score. Only the lender you choose will run a full credit check, and only after you’ve decided to proceed.
No fees, ever: We’ll never charge you for using PaydayUK. If anyone asks for upfront fees for a loan, be very careful. Legitimate brokers and lenders don’t work that way.
What are the alternatives to 3-month loans?
A 3 month loan might be exactly what you need, but it’s worth knowing about other options too. If three months feels too short, you might find a longer term more comfortable. If you need a specific amount, we have pages dedicated to different loan sizes.
Different loan terms: For lower monthly payments spread over a longer period, consider a 6 month loan. You’ll pay more interest overall, but each monthly payment will be smaller and easier to manage. If you need even more time, 12 month loans offer the smallest monthly payments with a full year to repay.
Different loan types: If you’re looking for flexible repayments, instalment loans let you spread the cost over regular payments. For those worried about their credit history, our bad credit loans page explains how specialist lenders can help.
Specific amounts: Looking for a particular sum? Lenders on the panel offer from £50 to £5,000. A £300 loan over three months is one of the most popular short-term arrangements we help with. A £400 loan or £500 loan is also popular for mid-sized emergencies.
Rates
Rates from 9.3% APR to 1,292.1% APR. The rate you’re offered depends on your individual circumstances.
Free, independent debt help
If you are struggling with debt or money worries, free help is available. It is confidential and will not affect your credit file.
-
MoneyHelper
Free, impartial money and debt guidance, backed by government, including a debt advice locator.
-
StepChange
Free, confidential debt advice and managed debt plans, online or over the phone.
-
National Debtline
Free, independent advice on dealing with debts, with fact sheets and sample letters.
-
Citizens Advice
Free help with debt, benefits and housing, in person, by phone or online.
0800 144 8848 (England; Wales 0800 702 2020)
If you're unsure whether borrowing is right for you, our eligibility criteria page explains who lenders can consider.
Three months is short - what does that mean in practice?
A 3 month term means a lower total cost than a longer loan, but bigger monthly payments. The main question is whether each payment fits your budget.
Read more
Each payment is a bigger share of a single month, so the affordability question is sharper.
You pay interest for less time, so the total repayable is lower than on the same sum over a year.
There are only three dates to manage, which makes it easier to keep track of.
There is less room for circumstances to change, which cuts both ways.
Settling early saves less than on a long agreement, because there is less interest left.
A missed payment on three is a third of the schedule, so the margin is thinner.
It suits a gap you can already see the end of, rather than an open-ended shortfall.
If the payments fit, a shorter term is the cheaper way to borrow the same money. If they do not quite fit, that is worth knowing before you sign rather than in month two.
How it works
We know you need your money as soon as possible. That's why we have designed our website to be fast and simple.
-
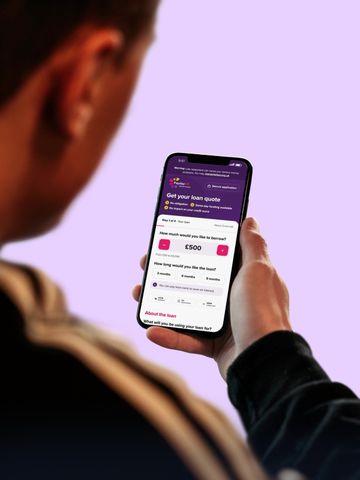
Apply online
Fill out our short, secure form and search a panel of FCA-regulated lenders to see the offers available to you.
-
Check your offer
Once you have your offer from the lender, you can review the offer and get your cash.
-
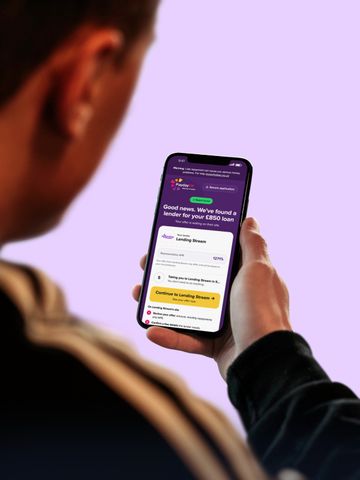
Get your money
Once accepted, your money can often be paid into your account the same day.
We've helped out thousands of people...
Rated 4.8 / 5 • 8,088 reviews
Showing our 4 & 5 star reviews
 Read our reviews on Trustpilot

3-month loans: amounts and terms
Check eligibility Soft search. Won’t affect your score
Representative 91% APR.
Loan guides
These guides will help you find out more about the different types of loan and lenders available.
-
What to compare beyond the APR, from the total you'll repay to what happens if a payment fails.
-
Understand Annual Percentage Rate and how it affects your loan costs.
-
Avoid scams and find FCA-authorised lenders. Learn the safe way to apply online.


Frequently asked questions about 3-month loans
Can I get a 3 month loan from any lender?
3 month loans come from specialist short-term lenders. Traditional high-street lenders don’t typically offer such short-term loans. The shortest term a conventional lender will usually accept is 12-months, and these will often come with strict criteria you have to meet in order to qualify.
Payday UK searches a panel of direct lenders in one application. If you’re weighing up where to apply, it helps to know the difference between lenders and brokers.
How much can I borrow over 3 months?
You can apply to borrow anything from £50 to £5000. Shorter periods are usually for smaller amounts like a £100 loan or £200 loan, while people borrowing more significant amounts like a £1000 loan typically opt for a longer repayment period to make the payments more manageable.
Can I get a 3 month loan with bad credit?
A poor credit history doesn’t rule out a 3 month loan, but approval is never guaranteed. Some lenders on the panel specialise in borrowers with a poor credit record. They look more closely at what you can afford now than at past problems, and one application lets several lenders consider you.
What happens if I can't make a repayment?
If you can’t make a repayment on your 3 month loan, contact your lender straight away, as many will work with you to find a solution. A missed payment can lead to fees, damage your credit score and make money problems worse. Free debt advice is available from MoneyHelper and StepChange.
How is a 3 month loan different from a payday loan?
Traditional payday loans are usually repaid in one lump sum on your next pay day. 3 month loans spread the repayment across three monthly instalments, making each payment smaller and more manageable.
Do I need a guarantor for a 3 month loan?
You don’t need a guarantor for a 3 month loan through Payday UK, because the loans available through the panel are unsecured. They’re no guarantor loans, so you won’t need to ask family or friends to co-sign. If you’d rather have someone back your borrowing, guarantor loans work differently.
Can I apply if I'm self-employed?
You can apply for a 3 month loan if you’re self-employed, as long as you have a regular income. Lenders will want evidence that your income is steady enough to cover all three repayments, so you may need to provide recent bank statements or other documents, such as a tax return.
