Trusted by 3 million UK customers
6-month loans
Making it happen.
Six months to repay, splitting the cost without stretching it out.
-
3 million
customers helped
-
4,500+
applications a daySee the footnote substantiating this figure
-
Excellent
4.8 out of 5 · 8,132 reviews on
What happens after I click?
- You complete one short, secure form.
- A soft search checks your eligibility. Your credit score isn't affected.
- No one will call you.
- If accepted, you see your offer and choose whether to accept.
- We do not charge you a fee for using PaydayUK.
-
4,500+
applications every daySee the footnote substantiating this figure
-
Quick
same-day payout if approved
- CCTA Member
- ico. Registered
- GDPR Compliant
Excellent
4.8 out of 5 · based on 8,132 reviews
- CCTA Member
- ico. Registered
- GDPR Compliant
Representative example: Amount of credit: £500 for 6 months at £100.22 per month (final payment £100.21). Total amount repayable of £601.31 Interest: £101.31 Interest rate: 66.49% pa (fixed). Representative 91% APR. Rates between 9.3% APR and maximum 1292.1% APR - your no-obligation quote and APR will be based on your personal circumstances. Credit broker, not a lender. Payday UK (Payday Loans Ltd) is an appointed representative of Flux Funding Limited, which is authorised and regulated by the FCA (FRN 806333).
understanding 6 month loans
What is a 6-month loan?
A 6 month loan is an instalment loan you repay in six monthly payments, instead of one lump sum. A 6 month loan gives you breathing room to manage repayments alongside your regular bills and commitments.
Read more
Payday UK is a credit broker, not a lender. We connect you with FCA-regulated lenders offering 6 month loans from £50 to £5,000, with a representative APR of 91%. Lenders on the panel start with a soft search, so checking won't affect your credit score.
Six payments make each instalment smaller than over three months, without carrying the debt for a full year. You apply once and Payday UK searches a panel of lenders for options suited to your circumstances.
Soft credit check only. No impact on your credit score. See your options in minutes.
Check eligibility Soft search. Won’t affect your score
How do 6-month loans work at Payday UK?
Payday UK searches its lender panel for a loan for 6 months that fits your circumstances, and you then apply with the lender you choose.
You borrow a fixed amount and repay it over six equal monthly payments. Each payment includes a portion of what you borrowed plus interest, making budgeting straightforward.
Read more
Here is exactly what to expect when you apply:
Step 1: Complete the online form.
Enter your personal details, how much you want to borrow, and select 6 months as your repayment term. The form takes about two minutes.
Step 2: Instant soft search.
The lenders on our panel run a soft credit check to assess your eligibility. This takes seconds and will not affect your credit score. Other lenders cannot see it.
Step 3: View your options.
If lenders from our panel can help, you will see what is available. Each offer shows the interest rate, monthly payments, and total cost. Take your time to compare.
Step 4: Choose your lender.
Found an offer you like? Click through to complete your full application with that lender directly.
Step 5: Final credit check.
The lender runs a full credit check and affordability assessment. This check will appear on your credit file.
Step 6: Decision and funding.
If approved, the lender transfers your funds. Many offer same-day payments, so you could have the money within hours.
No matches? No problem. If we cannot find suitable lenders right now, your credit score remains untouched because lenders only performed a soft search.
If a lender gets something wrong - a payment taken that you did not authorise, an affordability check that plainly did not happen, or a term you were never told about - complain to the lender first. It has eight weeks to send you a final response. If that does not settle it, you have six months to take the complaint to the Financial Ombudsman Service, which is free for you to use and can order the lender to put things right.
How 6-month loans work through Payday UK
Here at Payday UK, we make finding your 6-month loan as straightforward as possible to help smooth out life’s road bumps.
-
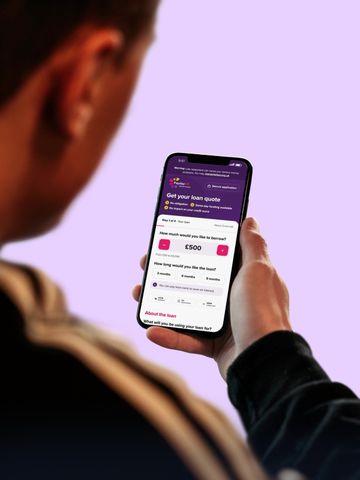
Apply online
Fill out our short, secure form and search a panel of FCA-authorised lenders and brokers to see the offers available to you.
-
Check your offer
Lenders check what you can afford. Compare the total repayable before you accept.
-
Get your money
If you’re approved and accept, the lender can often pay the same day.
Who can apply for a 6-month loan?
Each lender also has its own loan eligibility criteria, which help it decide whether it can lend to you responsibly.
To apply, you need to:
Read more
Be at least 18 years old
Be a UK resident with proof of address
Hold a UK bank account with a valid debit card, so the lender can verify your identity and send the funds
Have a regular income from employment, self-employment, or benefits. Some lenders on the panel also offer loans for people on benefits
Provide a valid email address and UK mobile number
Not currently be in bankruptcy or an Individual Voluntary Arrangement
Lenders use your income information to check that you can afford the monthly repayments without falling into financial difficulty.
Lenders on our panel set their own criteria. Our panel includes lenders who specialise in helping people with past credit difficulties. They focus more on your current affordability than historical credit issues.
If you are unsure whether you qualify, using our eligibility checker costs nothing and will not affect your credit score. You can see potential options in minutes without any risk.
Apply now
Enter an amount in pounds, from £50 to £5,000.
Will I be approved?
We know you need your money as soon as possible. Check where you stand in 3 minutes with a soft search that leaves no mark other lenders can see.
Check eligibility Soft search. Won’t affect your score
How much does a 6-month loan cost?
Check the total cost before you sign, not just the monthly payment.
Our representative APR is 91%. APR stands for Annual Percentage Rate and represents the total cost of borrowing over a year, including interest and any fees.
Read more
The representative example near the top of this page is a 6 month loan, so it shows the cost at this term.
Payday UK never charges you any fees for using our service. We are paid by lenders when a loan completes, so there are no application fees, broker fees, or hidden charges for you to worry about.
Missing payments can cause serious money problems and may affect your credit rating for up to six years. Always contact your lender immediately if you are struggling to make a payment.
Can I get a 6-month loan with bad credit?
Approval is never guaranteed, but a poor credit score doesn't rule you out of a 6 month loan on its own. Many high street banks and mainstream lenders turn down applications based solely on credit scores, leaving people with limited options.
Read more
Payday UK works with lenders who take a different approach. While credit history is considered, our panel includes specialists who focus primarily on your current financial situation and ability to afford repayments.
Your past credit difficulties do not have to define your borrowing options today. Lenders assess factors like your current income, existing financial commitments, and overall affordability when making their decisions.
If you have experienced CCJs, defaults, or missed payments in the past, it helps to know how to get a loan with bad credit before you apply. The soft credit check lets you see what options might be available without risking further damage to your credit file.
Successfully repaying a 6 month loan can actually help rebuild your credit score over time. Each on-time payment demonstrates responsible borrowing behaviour to credit reference agencies. However, this should never be the primary reason for taking out a loan.
How long does a 6-month loan application take?
A 6 month loan application takes around two minutes to fill in, and most people see their matched options within a few minutes.
Our application process is designed to be as quick and straightforward as possible. You provide basic personal details, information about your income and employment, and specify how much you want to borrow.
Read more
Once submitted, your details go to the lender panel straight away. Lenders run a soft credit check at this stage, and most people see their options within a few minutes.
If you accept a loan offer and are approved following the lender’s full credit check, funds are typically sent the same business day. Once a lender approves you, payout often happens the same day, but it depends on the lender and your bank. If speed is your priority, it's worth knowing how to get a same day loan and what can slow a payout down.
Applications are processed 24 hours a day, 7 days a week, 365 days a year. However, funding on weekends or bank holidays may be delayed until the next working day depending on the lender and your bank.
What can you use a 6-month loan for?
Six months suits a one-off cost too big for one pay packet, but not worth a year of payments. Common examples:
Read more
Car repairs: Your car fails its MOT or breaks down unexpectedly. Without it, you cannot get to work. A 6 month loan covers the repair costs and lets you spread the payment across several pay days.
Home emergencies: The boiler stops working in January. The washing machine floods the kitchen. These repairs cannot wait, and a 6 month loan provides the funds to sort them quickly.
Unexpected bills: Sometimes bills arrive that you were not expecting, or they are higher than usual. A 6 month loan can bridge the gap until your finances balance out again.
Medical or dental costs: NHS waiting lists mean some people turn to private treatment. Dental work, glasses, or other health costs can crop up without warning.
Pet emergencies: Vet bills can be expensive, especially if your pet needs surgery or ongoing treatment. Many pet owners use short-term loans to cover these costs.
Essential travel: A family emergency might require you to travel at short notice when you do not have the funds immediately available.
These loans work best for genuine emergencies where you need funds quickly and can afford to repay over the following months. They are not suitable for long term borrowing needs, discretionary spending, or situations where you are already struggling financially.
Before applying, consider whether borrowing is truly necessary. Could you wait until payday? Is there a payment plan available from whoever you owe money to? Could friends or family help? Only borrow if you are confident you can meet all the repayments.
What are some alternatives to a 6-month loan?
A loan is not always the right solution. Before committing to borrow, it is worth considering other options that might cost less or suit your situation better.
Read more
Credit unions often offer more affordable lending rates than commercial lenders. These not-for-profit organisations exist to serve their members and may be able to help even if you have limited credit history. Find your local credit union at findyourcreditunion.co.uk.
If you are struggling with bills, contact the company you owe money to. Many utility providers, councils, and service companies offer payment plans or hardship schemes. They would often rather arrange manageable payments than chase a debt.
Free debt advice is available if you are worried about your finances. It is confidential, and an adviser can help you make a plan.
Other alternatives to consider:
Asking family or friends for a short term loan
Checking if you are entitled to benefits or grants you are not claiming
Selling items you no longer need
Using savings if you have them, rather than paying interest on borrowing
Negotiating an overdraft extension with your bank
If you do decide a loan is right for you, our 3 month loans or 12 month loans might also suit your needs depending on how much you want to borrow and your preferred repayment schedule.
Free, independent debt help
If you are worried about your finances, free debt advice can help you understand your options and make a plan. It is confidential and will not affect your credit file.
-
MoneyHelper
Free, impartial money and debt guidance, backed by government, including a debt advice locator.
-
StepChange
Free, confidential debt advice and managed debt plans, online or over the phone.
-
National Debtline
Free, independent advice on dealing with debts, with fact sheets and sample letters.
-
Citizens Advice
Free help with debt, benefits and housing, in person, by phone or online.
0800 144 8848 (England; Wales 0800 702 2020)
How do 6-month loans compare to other terms?
Choosing the right repayment term affects both your monthly payment and the total cost of borrowing. Here is how 6 month loans compare to other options.
Read more
Shorter terms like 3 months mean higher monthly payments but less interest overall. If you can comfortably afford larger monthly amounts, a shorter term saves money. For example, borrowing £500 over 3 months costs less in total interest than borrowing the same amount over 6 months.
Longer terms like 12 months reduce your monthly payment, making budgeting easier. However, you pay more interest over the life of the loan. This option suits larger borrowing amounts like £1000 loans where the monthly payment on a shorter term would be unaffordable.
Six months often represents a sensible middle ground for amounts between £500 and £1,500. The monthly payments remain manageable without extending the debt for too long.
Lenders on the panel offer terms from 3 to 36 months and amounts from £50 to £5,000. When you apply, you can pick your term and see how it changes the monthly payment and total cost.
What are some tips for repaying a 6-month loan?
Six months is six payment dates, and most of the difficulty people have with a short-term loan is practical rather than financial. A few minutes of setup at the start removes most of it.
Read more
Line the payment date up with the day after you are paid, not the day before.
Check what else leaves your account that week - rent, energy and council tax cluster.
Know whether the lender collects by direct debit or continuous payment authority, because the two behave differently.
Put the six dates in a calendar. A missed payment is usually a forgotten one.
Keep a small buffer in the account rather than the exact amount.
If the date is wrong, ask to move it early; most lenders can.
Tell the lender before a payment fails, not after - it has to treat you fairly if you are in difficulty.
If you come into money, ask for a settlement figure. Settling early rebates interest you have not yet reached.
None of this changes what the loan costs. It changes how likely you are to reach the end of it without a fee or a mark on your file, which is worth more.
What happens across the six months
Six payments is the whole agreement. This is what each stage involves, what you can do at that point, and which Consumer Credit Act rights apply. No costs here: those come from the lender's own offer.
Read more
| Point in the six months | What is happening | What you can do | Why it matters at this term |
|---|---|---|---|
| Days 1 to 14 | The agreement is live and the money is usually in your account. | Withdraw. You have 14 days to pull out of a regulated credit agreement. Tell the lender, then repay what you borrowed plus interest for the days you had it, within 30 days. | This is the only stage where you can undo the decision rather than settle it. If the bill got covered another way, step back here. |
| Payment 1 of 6 | The first instalment is collected, usually about a month after the funds land. | Check the collection date sits after your pay date, and ask the lender to move it before a payment fails rather than after. | One sixth of the plan clears here. A date that sits awkwardly against your wages will do so five more times, and six months is too short to grow out of it. |
| Payment 3 of 6, the halfway point | Half the instalments are behind you and the balance is falling. | Ask the lender for a settlement figure. You can repay early, in full or in part. | You can repay early at any time and pay less interest. No early repayment charge applies to loans arranged through us. Ask the lender for a settlement figure first. It can include up to 28 days' extra interest. |
| A payment that fails | The shortfall has to be made up across the instalments that remain. | Contact the lender before the payment date, not after. They can often move a date or agree a revised plan. | Once you are behind by the equivalent of two payments the lender must send you a notice of sums in arrears. On six instalments that is a third of the agreement, so there is very little room to recover inside the term. |
| Payment 6 of 6 | The final instalment clears the agreement. | Check the lender marks the account settled and that it shows that way on your credit report. | The closed account stays visible to other lenders for six years. A six-month agreement is a short record, so how it ends carries weight. |
These rights come from the Consumer Credit Act 1974: withdrawal, early settlement and notice of arrears. They apply whichever lender you borrow from. PaydayUK is a credit broker, not a lender, so the agreement is with the lender. Payment dates, plans and settlement figures come from them. The stages here are a guide, not lender criteria.
What should I think about before borrowing over 6 months?
Borrowing money is a serious commitment. Before applying for any loan, take time to consider whether it is the right decision for your circumstances.
Ask yourself these questions:
Read more
Can I definitely afford the monthly repayments for six months?
Have I checked my budget to ensure the payments will not cause problems?
Is this expense genuinely urgent, or could I wait and save instead?
Have I explored all the alternatives to borrowing?
What happens if my income changes during the repayment period?
If you take out a loan and later find yourself struggling, contact your lender immediately. They may be able to adjust your repayment plan. Ignoring the problem will make things worse and could result in additional fees and damage to your credit rating.
Check eligibility Soft search. Won’t affect your score
We've helped out thousands of people...
Rated 4.8 / 5 • 8,132 reviews
Showing our 4 & 5 star reviews
 Read our reviews on Trustpilot

6-month loans: amounts and terms
Check eligibility Soft search. Won’t affect your score
Representative 91% APR.
Loan guides
These guides will help you find out more about the different types of loan and lenders available.
-
Understand Annual Percentage Rate and how it affects your loan costs.
-
Personal loans for students: types, criteria, and when they're worth it.
-
Find out why no credit check loans don’t exist in the UK and how lenders assess affordability. See the legitimate options if you have bad credit or no credit history.


Frequently asked questions about 6-month loans
Is a 6 month loan a payday loan?
A 6 month loan isn't the same as a traditional payday loan, although both are types of short term credit. Traditional payday loans are usually repaid in full on your next payday. A 6 month loan is an instalment loan, so you repay it over six monthly payments. You get longer to repay, and each payment is smaller.
Am I better off using my overdraft than 6 month loans?
An overdraft usually charges less interest than a 6 month loan, but it can be harder to clear. You can keep borrowing back what you repay, so the debt may run on indefinitely. A 6 month loan has a set end date. Overdrafts can be slow to arrange and hard to get with bad credit, so they suit disciplined borrowers.
Can I get a 6 month loan if I have bad credit?
You may still get a 6 month loan with bad credit, though approval is never guaranteed. Several lenders on the panel focus on what you can afford now, not just what happened in the past. Many offer unsecured loans, so you won't usually need guarantor loans. The whole application is online, which suits anyone looking for quick and easy loans
How much can I borrow with a 6 month loan?
You can borrow from £50 to £5,000 with a 6 month loan through Payday UK. The amount you are offered depends on your individual circumstances, including your income and credit profile. Each lender on the panel sets its own limits. Lenders assess affordability to ensure you can manage the repayments, so you may be offered less than you asked for.
What happens if I cannot make a repayment?
If you can't make a 6 month loan repayment, contact your lender before the payment date, not after. They may offer temporary solutions such as adjusted payment schedules.
How do I know if a 6 month loan is right for me?
A 6 month loan is right for you if you need money for a genuine one-off cost and can afford six monthly repayments. Like emergency loans, it’s meant for urgent needs, not regular or everyday spending. If you are already struggling with debts, or unsure whether you can meet the repayments, free debt advice is usually a better first step.
